

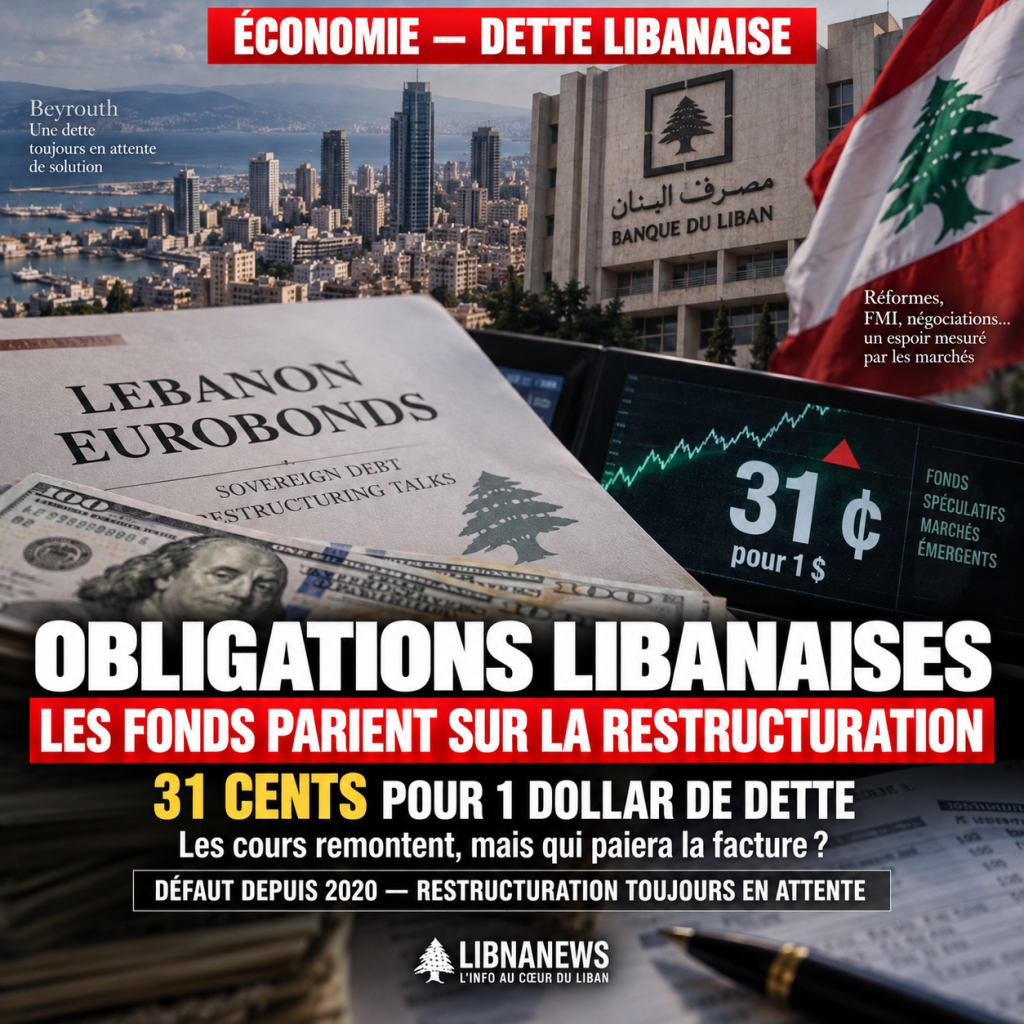
27 to 31 cents: what the market actually buys
The Lebanese State’s international bonds approached 31 cents at the beginning of October 2026 for one dollar in nominal value. This level, which has been the highest in approximately six years, contrasts with the non-payment announced in March 2020 under Hassan Diab’s government. However, progress does not mean that the deadlines are again being met or that the Consolidated Revenue Fund can borrow normally. First, it indicates that some investors agree to pay more today for a debt whose future settlement remains uncertain. This price shift is an important financial information: it reflects a revision of expectations, not an acquired restoration of the state’s solvency.
The quoted quotations show a range of 27.13 to 29.25 cents, compared to 27.25 to 29.50 cents at the end of the previous week. These intervals should be read with caution: they do not necessarily represent identical transaction prices for all issues. Bonds differ in terms of maturity and conditions. The announcement of a price close to 31 cents does not mean that the entire debt swaps at this level. However, it notes a renewed interest in Lebanese titles. The difference between the quotations observed and the threshold mentioned also shows why a market movement cannot be summed up at a single price.
Emerging market funds take a stand on negotiations that have not been successful
The movement is associated with net purchases of investment funds active in emerging markets. Their interest should not be confused with that of a lender financing a new public project. On the secondary market, an investor buys a security already issued from another holder. The Lebanese State does not receive the proceeds of this transaction. The new purchaser, on the other hand, obtains a claim and the right to participate, under the applicable conditions, in negotiations on its future treatment. The change in ownership can therefore change the expectations and strategies of creditors without bringing a single additional dollar to the budget.
A 31 cent purchase can be profitable if the value ultimately recovered exceeds the price paid, taking into account the time elapsed, the costs and the risk. For illustrative purposes, a security purchased at $31 per 100 nominal dollars would generate a gross gain of $9 if its final settlement reached $40. If the recovery was only $20, the investor would incur a gross loss of $11. These examples do not prejudge any proposed restructuring. They show the calculation that can attract specialized funds: buy a haircut debt, then bet on a more favourable outcome than that implicit in the purchase price.
The actual volume exchanged, the identity of the purchasers and the concentration of the securities are not detailed in the available information. It would therefore be inappropriate to state that a particular fund now controls a decisive part of the obligations. The distinction counts for a survey of beneficiaries: the increase can benefit sellers who immediately realize their surplus value, as well as holders who see the value of their portfolios grow on paper. It can also expose new buyers to losses if negotiations fail.
Banking reform and the Monetary Fund: the announcements that fuel optimism
Procurement is aligned with the progress announced on banking sector reform. Investors would have welcomed the legislative changes discussed in Lebanon, as well as the prospects for a resumption of trade with the International Monetary Fund. A mission of the Fund visited Lebanon from 15 to 18 September 2026, according to the information published. The discussions are presented as a sign of improved technical dialogue. Minister of Finance Yassine Jaber also reported encouraging exchanges with the institution’s officials in the United States. However, the positive assessment of certain reforms must be distinguished from the conclusion of a new agreement: the information examined does not confirm the signing of a definitive programme.
Banking reform and sovereign debt are linked but not the same. The treatment of bank losses, Bank of Lebanon claims and depositors’ rights cannot be treated as repayment of the State’s international obligations. A solution on one side can make negotiations more credible without automatically settling the other. However, the market can react to the impression that several long blocked files are advancing simultaneously. This is precisely what makes the rise in prices fragile: an anticipation of progress may precede their legal and financial translation by several months or even years.
A chronological anomaly appears in the economic text examined: it refers to a measure dated « current August 12 » while the edition is dated October 8. This wording alone does not allow for the determination of whether the author refers to a previous decision or whether a drafting error has been made in the publication. It would be imprudent to transform this passage into a certain date of entry into force. In order to assess reforms, a distinction must be made between parliamentary voting, enactment, implementing legislation and their effective implementation.
Why higher bonds can complicate debt negotiation
The rise in the price of securities is often presented as good news. For a defaulting State, the reasoning is less simple. If creditors acquire their obligations at higher prices, they may be less inclined to accept a settlement that is lower than their purchase cost. Historical owners, on the other hand, can compare any offer with the prices observed in the secondary market. The level of 31 cents does not legally impose any recovery rate, but it becomes a reference point in the discussions. An increase fuelled by optimism can thus increase investor expectations even before the state has stopped its real capacity to pay.
There are three dimensions that are often mixed in the public debate: the nominal amount due, the market value and the sum that could be recognized in a restructuring agreement. A nominal amount of $100 purchased $31 does not automatically reduce the State’s contractual debt to $31. Conversely, the creditor does not necessarily have a guarantee to recover the $100. The solution would depend on the terms of an agreement, the applicable legal rules and the capacity to repay. To present the rating as the amount that Lebanon will have to pay would therefore be misleading.
The issue of interest accumulated since the 2020 default makes the equation more difficult. The available information refers to their possible treatment in the discussions, without providing a complete table by issue or consensus calculation. However, the fate of unpaid interest can significantly change the value of a proposal. An offer only for the principal is not directly comparable to an offer incorporating a fraction of the coupons due. Before announcing a discount rate or savings for the Consolidated Revenue Fund, you need to know the basis of calculation and the maturity to which it applies.
Who wins, who waits, and who will bear the bill?
The first possible winners are investors who already held the securities before they were raised. Those who sell after the increase can turn a potential gain into a realized gain. Recent buyers, for their part, take the bet that final negotiation will give them a recovery over the cost incurred. However, the market does not reveal in the documents examined the exact distribution between specialized funds, financial institutions and other carriers. Nor is it possible to establish the share of securities held indirectly by Lebanese actors. Any designation of beneficiaries would therefore be speculative.
For the state, the increase does not create any immediate revenue. It may signal renewed confidence in the possibility of an agreement, but it may also increase the expectations of some creditors. For taxpayers and users of public services, the challenge is more distant: too much restructuring could reduce the budgetary margins available for reconstruction, infrastructure and social spending. Conversely, a credible solution compatible with the country’s capabilities could reduce financial uncertainty. The collective benefit will depend on the content of the agreement, not only the performance of a rated title.
The adjustment of bonds takes place in an economy that must simultaneously rebuild housing, finance public services and restructure its banking system. An economic analysis published in the same series of newspapers suggests that inflation could reach about 17.5 per cent by the end of 2026, according to a World Bank forecast. This figure is not a measure of bond prices. However, it recalls that the improvement of a financial indicator may coexist with a deterioration in purchasing power. An increase in the secondary market should not mask the difficulties that households still face.
The figures and documents needed to divide the optimism of speculation
In order to really appreciate the rise in securities, a number of information is still missing: the volume of transactions, the breakdown of prices by issue, the structure of the holders, the amount of interest due and the trading position of the State. The macroeconomic assumptions used to determine what Lebanon can reasonably repay should also be known. Without these data, it is possible to describe the resumption of procurement, but not to quantify the overall gain in funds or the final cost to public finances. The absence of these elements constitutes a substantial limitation of the investigation, not a technical detail.
As of October 8, 2026, the threshold close to 31 cents is therefore a change in expectations rather than debt settlement. Funds interested in Lebanese securities bet on a more favourable outcome, fuelled by the announcements of reform and the resumption of dialogue with the International Monetary Fund. The State still faces the initial problem of negotiating debt treatment compatible with its resources and economic reconstruction. The decisive question is not whether the market has won a few cents, but what part of the future value will ultimately be given to creditors and under what conditions.

Comments