
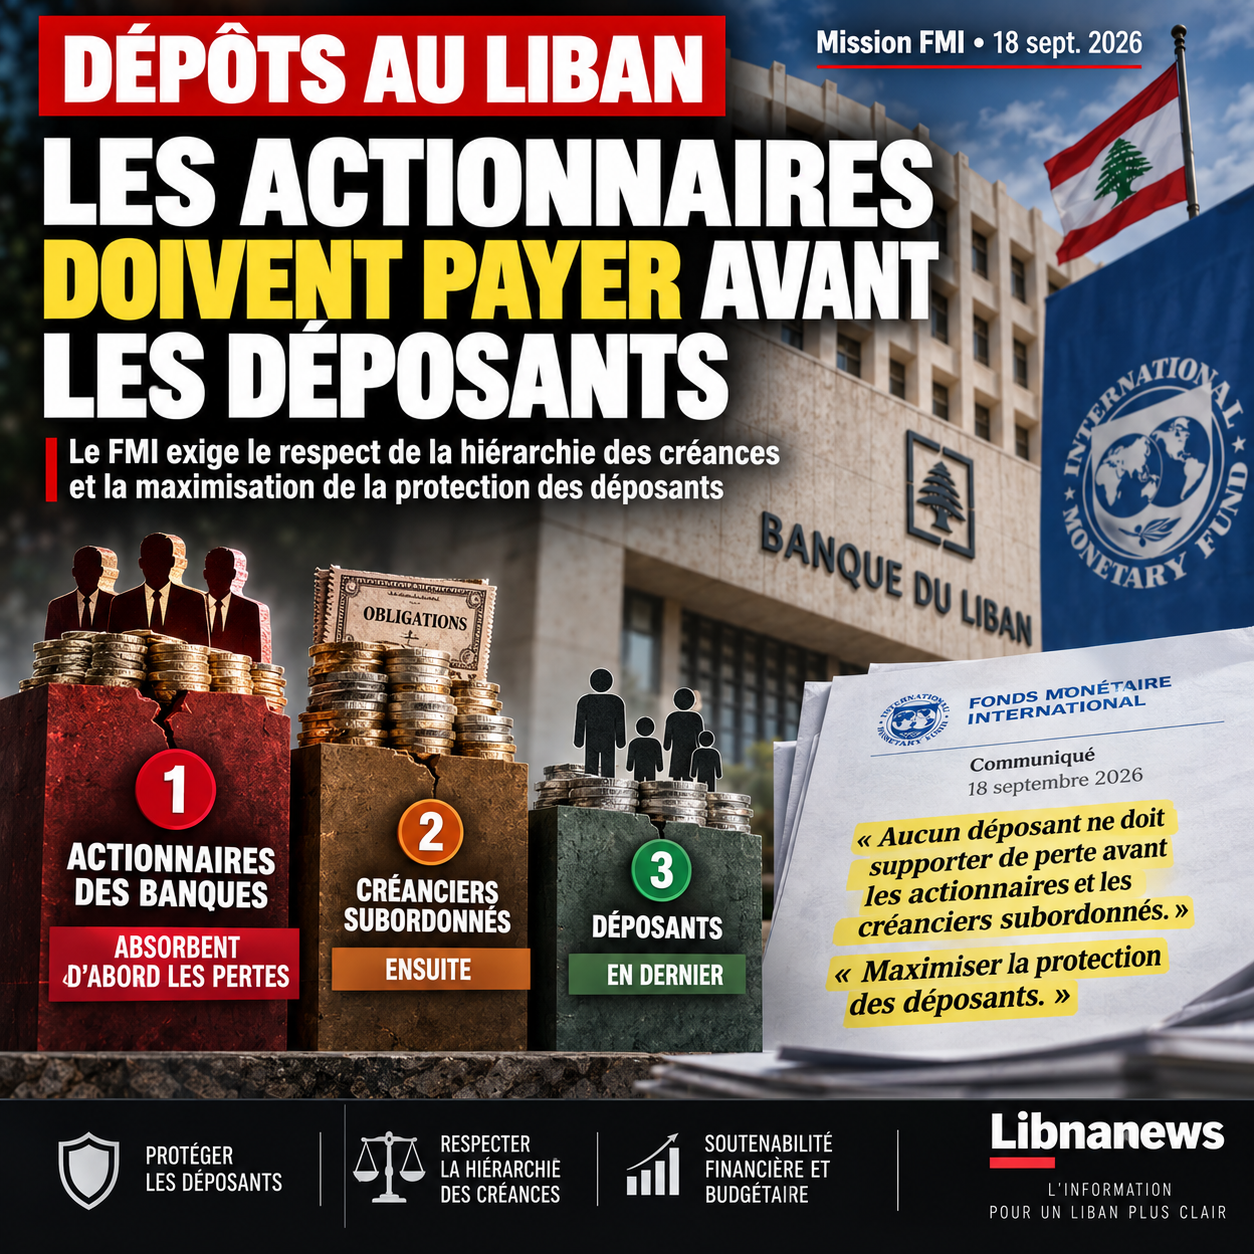
The battle around Lebanese bank deposits is no longer just about billions of dollars. It is also played on the information field. While a media talk presents the reforms negotiated with the International Monetary Fund as an attempt to make depositors pay, the official position of the IMF says something else: losses must first reach the shareholders and subordinate creditors of banks. This difference is essential when Beirut negotiates the law on financial stabilization and deposit return.
The last mission of the International Monetary Fund to Lebanon was completed on Friday, September 18, 2026. The press release provides a direct means of verifying what the international institution is asking for regarding thedeposits in Lebanon.
The principle formulated by the IMF is specific. The hierarchy of claims must be respected. No depositor must absorb losses before the shareholders of the banks and their lower-ranking creditors.
This position does not guarantee that each depositor will recover immediately and in full each dollar entered in its account. Nor does it allow us to know today what final amount can be returned. But it contradicts a presentation that the IMF would first seek to take money from depositors to preserve bank capital.
This is even the reverse on a fundamental point: shareholders’ capital is in front of deposits in the order of loss absorption.
Deposits in Lebanon: IMF reaffirms depositor priority
The wording published after the mission from 15 to 18 September leaves little room for ambiguity.
IMF calls on Lebanon to align the future law on financial stabilization and deposit return with international standards. The stated objective is to « maximize the protection of depositors », while preserving the country’s financial and budgetary sustainability.
Above all, the Fund reiterates the principle that no depositor should bear any loss before shareholders and subordinated creditors.
This hierarchy is decisive.
A shareholder owns a part of the bank and benefits from any profits. Its investment has a capital risk in return. A depositor is a creditor of the bank. When an establishment becomes insolvent, these two categories cannot therefore be placed on the same plane.
In the IMF’s scheme, equity must be absorbed before a loss can go back to the depositors. The subordinated instruments also come before the latter.
This doctrine did not appear in September 2026. The IMF has been defending it for several years in the Lebanese case. Last February, he had already indicated that no loss should be attributed to depositors before it was attributed to shareholders or lower-ranking creditors.
The current debate cannot therefore be correctly summed up as a confrontation between, on one side, those who wish to save the deposits and, on the other, an IMF which seeks to confiscate them.
The reality is more complex.
What the IMF does not promise depositors
However, the reverse error must be avoided.
To say that the IMF places a priority on depositors over shareholders does not mean that the institution promises full repayment of all bank accounts. At the same time, the Fund insists on the resources actually available.
This is precisely the problem of the financial collapse that began in 2019.
Banks have commitments to their customers. They themselves hold large claims on the Bank of Lebanon. The central bank has accumulated considerable losses after years of financing the Lebanese economic and monetary model. The State, for its part, defaulted on its foreign currency debt in March 2020.
As a result, a large proportion of the dollars recorded in the banking system are no longer immediately available.
Future legislation must transform this into a legal and financial mechanism. It will have to determine what losses actually exist, what assets can be recovered and in what order the different actors must contribute.
This is where the real conflict lies.
Shareholders have an interest in preserving their capital as much as possible. Banks seek to limit their losses. The State wants to avoid a contribution that would make its debt unsustainable again. Depositors want to recover their assets. At the same time, the Bank of Lebanon must maintain sufficient liquidity to avoid further monetary destabilization.
Presenting this equation as a simple will to « take money from depositors » therefore masks the main question:who must first absorb the losses accumulated before 2019?
On this point, the IMF replied.
Shareholders are ahead of depositors.
A battle of interest behind the battle of words
This distinction becomes particularly important when criticism of the plan comes from media directly or indirectly linked to actors with economic interests in the financial sector.
Lebanon has a long history of strong interlinkages between banks, great fortunes, politicians and the media. This fact obviously does not allow an article to be declared false simply according to its owner. Information must be judged on the facts it presents.
But the ownership of a media is relevant information when it intervenes in a debate that may directly affect the economic interests of its owners or their associates.
It is even more so when it comes to the distribution of tens of billions of dollars in losses.
Readers must then be able to distinguish between three things: the official position of the IMF, the proposals of the Lebanese authorities and the arguments put forward by the banking sector.
Confounding them produces a misleading representation of the file.
The IMF position is available in black and white. It consists of respecting the hierarchy of claims and preventing a loss from being imposed on depositors before shareholders and subordinate creditors.
Why shareholders are at the centre of the conflict
The principle may seem technical. Yet its consequences are considerable.
Suppose a bank has assets insufficient to cover all its liabilities. If its capital remains artificially intact while part of the deposits is cancelled, savers bear a loss while the owners of the establishment retain their investment.
This is precisely what the IMF’s hierarchy seeks to prevent.
It means that owners of an unsustainable bank cannot normally retain their capital as if the institution were solvent, and then ask customers to absorb the deficit.
The reform of the banking resolution adopted in 2026 goes in this direction. In particular, it establishes a hierarchy between different categories of capital, creditors and depositors. Institutions must also be examined individually to determine their actual situation.
This approach is politically sensitive in Lebanon.
The collapse of 2019 not only destroyed the liquidity of the system. It has created a conflict of distribution between groups whose interests are now opposed.
Each dollar of loss charged to bank capital is a dollar borne by bank owners. Every dollar transferred to the state eventually weighs on public finances. Every dollar cut off from deposits directly affects a saver.
The debate on hierarchy is therefore not an accounting abstraction.
He determines who will pay.
Small depositors’ precedent
The protection of savers is also a constant feature of the IMF’s public position since the early negotiations with Beirut.
By 2022, the institution called for the full protection of small depositors and recalled the need to respect the hierarchy of claims. It also warned against excessive use of public resources.
This last question is important.
Massive use of government assets to recapitalize banks or repay accounts amounts to contributing the entire population, including Lebanese who do not have large bank deposits.
The IMF therefore considers that the protection of depositors should be reconciled with another requirement: not to transfer private losses to public assets without limitation.
This is one of the main differences with part of the Lebanese banking sector. For several years, some bank representatives have placed greater emphasis on the responsibility of the State and the Bank of Lebanon in the collapse of the system.
This public responsibility is part of the file. However, it does not remove the bank’s policy and does not automatically alter the order of loss absorption.
Where the defence of applicants may serve other interests
This is where public discourse becomes particularly delicate.
A banking actor can defend a solution presented as favourable to depositors while simultaneously defending an architecture that better protects bank capital or transfers part of the bill to the state.
Both objectives can even be wrapped in the same slogan: « Protecting deposits ».
Mechanisms should therefore be looked at rather than statements.
Who loses his capital first? Who recapitalizes viable institutions? What happens to insolvent banks? What contribution is requested from the State? What assets of the Bank of Lebanon can be mobilized? Which deposits will be repaid in cash and which will be repaid through financial instruments? On what calendar?
It is these answers that will help determine who actually supports the crisis.
The issue of media ownership then takes on a particular dimension. When an information body belongs to an actor linked to the financial system, this relationship alone does not demonstrate editorial manipulation. It is, however, a potential conflict of interest that the reader must know when evaluating a speech on the distribution of bank losses.
This precaution applies to all camps.
The Lebanese banking system also defends its capital
The banking sector has had an argument which it has repeated for several years: banks would not have created losses alone. They placed a considerable portion of their liquidity with the Bank of Lebanon and financed the State, while the authorities maintained a monetary model that had become unsustainable for years.
That argument must be heard.
But recognizing the responsibility of the State or the Bank of Lebanon does not automatically exempt shareholders from private institutions.
This is precisely what the IMF doctrine refuses.
Banks are private companies whose shareholders have collected profits during the years of profitability. The international principle of bank resolution is that their capital is also the first line of absorption when losses make the institution insolvent.
Thus, the conflict is less about the existence of losses than about their attribution.
And this distinction explains part of the violence of the current political and media debate.
Verifiable information after the mission of 18 September
The communiqué issued after the IMF mission now offers a particularly recent reference point.
The Fund welcomes the amendments to the Banking Resolution Act adopted by Lebanon. He now called for further work on the law on financial stabilization and return of deposits.
This second law is decisive since it must deal with the financial hole in practice.
IMF requests that it maximize the protection of depositors. It also calls for respect for the sustainability of public finances and the financial system. Finally, it explicitly reiterates that no depositor should absorb losses before shareholders and subordinated creditors.
These three elements must be read together.
They are not a promise of immediate and full reimbursement. Nor do they justify the opposite assertion that the IMF would first ask to sacrifice depositors in order to save banks.
The next step will be much more concrete. Parliament and government will have to translate this hierarchy into law and determine what resources are actually available to return deposits.
It is then that the positions will become measurable: no longer through slogans on the « protection of depositors », but by observing how shareholders, banks, the Bank of Lebanon, the State and, possibly, the different categories of depositors will really have to bear.