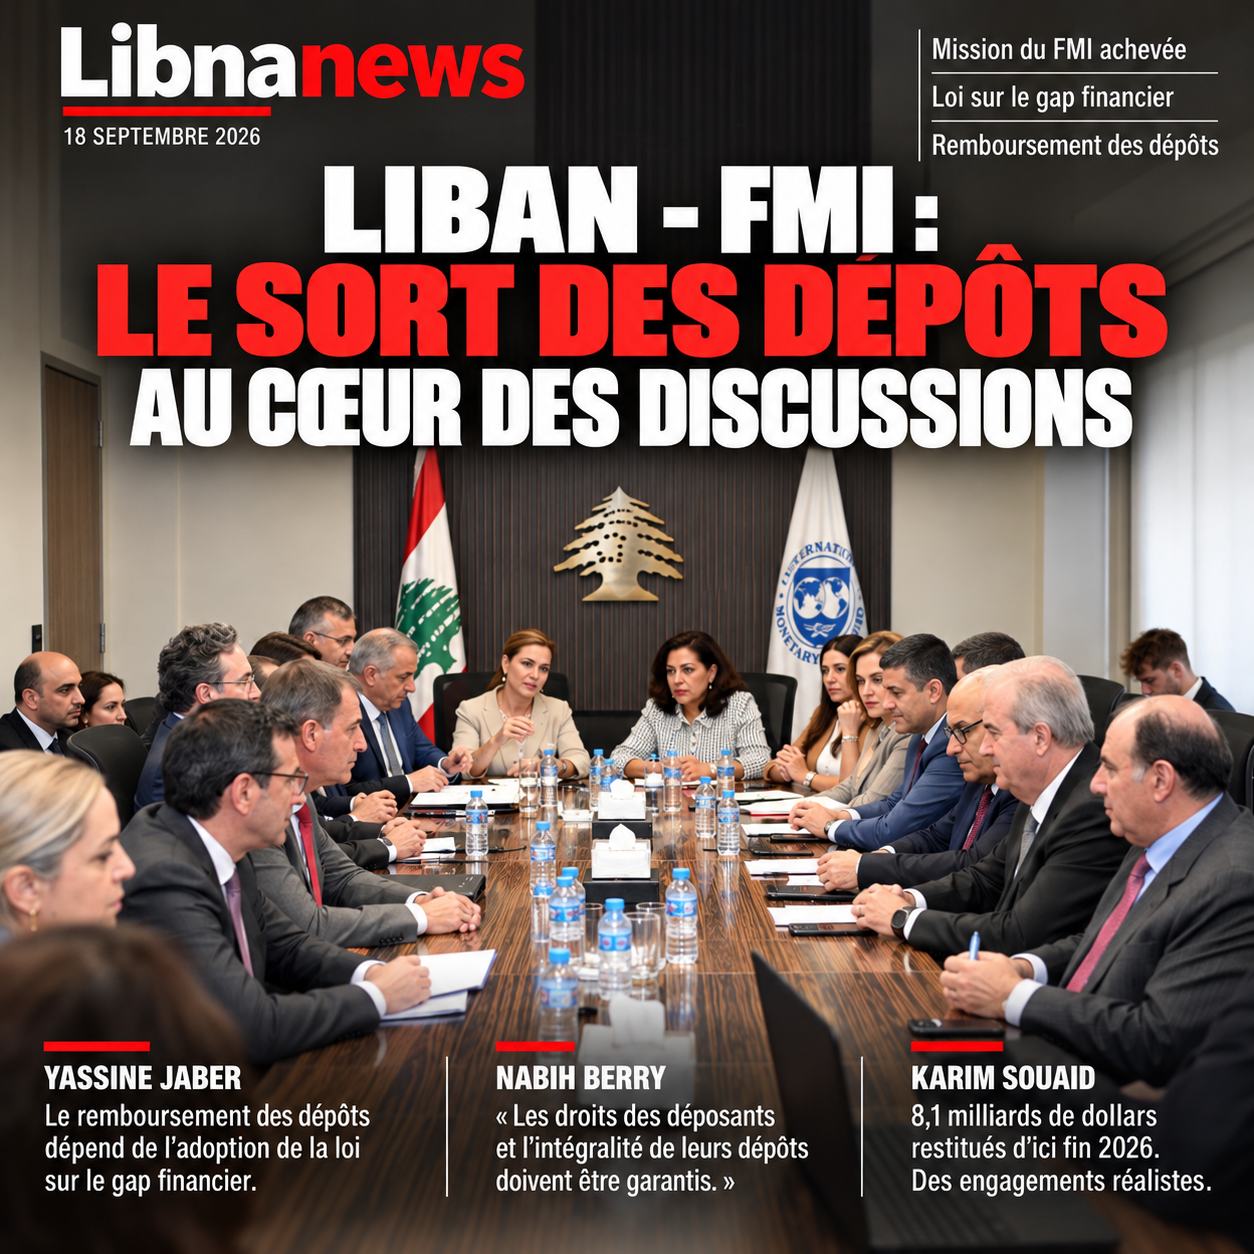
The mission of the International Monetary Fund concluded on Friday, September 18, four days of discussions in Lebanon with a priority: to move forward on the law that must allocate the losses accumulated since the financial collapse and pave the way for the repayment of depositors. Finance Minister Yassine Jaber now makes it clear that the beginning of the return of deposits depends on the adoption of this law. The Governor of the Bank of Lebanon, Karim Suaid, announces that $8.1 billion will have been returned to depositors by the end of 2026 through Circulars 158 and 166. But the central question remains: who will bear the tens of billions of dollars of system losses and how much can deposits actually be returned?
The day also revealed the political tensions surrounding the next text. In Ain al-Tiné, the head of the IMF mission, Ernesto Ramirez Rigo, the Speaker of the Chamber, Nabih Berry, affirmed that any law must guarantee « the rights of depositors and all their deposits ». This requirement comes as the Bank of Lebanon defends an approach based on the resources actually available. Karim Souaid stressed on Friday the need not to make promises to depositors that the institutions would not be able to deliver.
IMF completes four days of discussions in Lebanon
The IMF delegation held its meetings in Beirut from 15 to 18 September. Discussions took place mainly at the Ministry of Finance and the Phoenicia Hotel. They brought together Lebanese officials responsible for public finance, banking, taxation, debt, budget and customs, as well as representatives of the private sector.
The final meeting was held Friday at the Department of Finance. It brought together Yassine Jaber, Minister of Economy and Trade Amer Bisat, Governor of the Bank of Lebanon Karim Suaid, representatives of the Presidencies of the Republic and the Council of Ministers, and the relevant administrations. Ernesto Ramirez Rigo led the IMF delegation.
The immediate objective is not yet the signing of a final financial programme. Beirut first seeks to achieve aagreement at service level, orStaff-Level Agreement(SLA), with the Fund. Lebanon had already obtained such an agreement in April 2022, but was unable to meet the conditions for its transformation into a full IMF-funded programme.
The situation was different in 2026. Several long-requested texts have advanced, including on bank secrecy and restructuring of financial institutions. Parliament also adopted important changes to the banking restructuring framework in August. However, the most sensitive case remains open: that of the recognition and distribution of losses.
Financial Gap Act: text becomes decisive
Yassine Jaber confirmed on Friday that discussions with the IMF had focused on the financial gap bill. Behind this technical expression is the main unresolved problem since the collapse of 2019: the huge gap between the financial system’s dollar commitments and the assets actually available to honour them.
Commercial banks hold large claims on the Bank of Lebanon. They have simultaneous obligations to their applicants. The central bank itself has accumulated considerable losses after using the currencies attracted to the system for years to finance the state, maintain the parity of the pound and support the financial model. Finally, the state defaulted on its foreign currency debt in March 2020.
Determining the existence of losses is therefore no longer sufficient. The future law must determine how they will be recognized and distributed among the State, the Bank of Lebanon, banks, their shareholders and, according to the mechanisms finally adopted, depositors.
This explains why this law now conditions virtually all the next steps. Banking restructuring cannot be completed without knowing the real value of the assets of the institutions. Depositors cannot know the share and timing of their assets until the losses have been affected. And the IMF cannot conclude a sustainable programme with a financial system whose liabilities remain largely unresolved.
Jaber directly links repayments to the adoption of the law
Yassine Jaber established on Friday an explicit link between the adoption of the text and the return of deposits. According to the Minister of Finance, the start of the asset recovery process depends on the adoption of the Financial Gap Act.
This declaration is important because it places the reimbursement of applicants in a comprehensive legislative mechanism. Since 2019, withdrawals have been organized mainly by Bank of Lebanon circulars and by rules applied by institutions, without final settlement of accumulated liabilities.
The Minister considers that the new law should allow the transition from these interim mechanisms to an organized treatment of the crisis. He states that the Bank of Lebanon will have a central role in the process and that the Government will support the central bank in restructuring the sector, restoring deposits and restoring confidence.
Jaber nevertheless acknowledges that the parliamentary calendar may still delay the text. The government is working in parallel with Budget 2027, which is to be forwarded to Parliament on 2 October. The review of the financial gap project may therefore not begin immediately.
This constraint comes after seven years of crisis. On Friday, the Minister himself pointed out that the processing of the bank file could no longer be delayed.
Berry claims security for all deposits
A few hours earlier, Nabih Berry had placed a much stronger political demand on the table. The Speaker of the Chamber received in Ain el-Tiné Ernesto Ramirez Rigo, accompanied by the IMF Resident Representative in Lebanon, Yassine Said, and Councillor Maya Shueiri.
The meeting focused on the state of the negotiations after the adoption of the banking restructuring framework and the beginning of the study of the law concerning the financial gap. Nabih Berry reiterated to the Delegation that any text should guarantee the rights of applicants and their filings in their entirety.
This position will be decisive when the draft comes before Parliament. However, it immediately raises the issue of resources. Legally guaranteeing all depositors’ claims is not enough to create the tens of billions of dollars needed to repay them. The future arrangement will therefore have to specify who provides the assets to honour this guarantee, how long it lasts and how.
It is precisely on this point that negotiations with the IMF remain sensitive. The Fund has for several years defended a principle of loss hierarchy: shareholders and subordinated creditors must absorb losses before they can be imposed on depositors. During its mission in February 2026, the IMF had also stressed the need not to impose a contribution on the State that would make public debt unsustainable again.
The debate therefore does not focus solely on the protection of applicants. It focuses on how to make this protection financially feasible.
Karim Souaid: $8.1 billion returned at the end of 2026
Karim Souaid introduced a precise figure in this discussion on Friday. According to the Governor of the Bank of Lebanon,$8.1 billion will be returned to depositors by the end of 2026under circulars 158 and 166.
These two mechanisms allow certain categories of depositors to progressively access part of their foreign currency assets under limits and conditions defined by the central bank. They are one of the few channels still allowing a regular return of dollars from accounts blocked since the crisis.
However, the $8.1 billion must be interpreted correctly. It does not mean that the deposit crisis will have been resolved to the tune of 8.1 billion under the future law. It corresponds to the amounts that the Bank of Lebanon considers to have had progressively returned through the existing mechanisms until the end of 2026.
At the same time, the Governor states that there is a « clear mechanics » for dealing with deposits. However, he did not detail all the parameters on Friday. He stressed the need to build a mechanism compatible with the resources of the financial system.
Between Berry’s promise and Suaid’s caution
The statements of Nabih Berry and Karim Suaid thus highlight the two constraints that will be placed on the future law. The first is political and legal: to preserve as far as possible the rights of applicants. The second is accounting: to determine what resources actually exist to convert these duties into refunds.
The governor chose a prudent vocabulary on Friday. The Bank of Lebanon, he explained, is exploring the possibilities of repayment using a « rational » approach, while preserving the liquidity needed to operate the financial system. Work must continue even before the law is finally adopted.
Karim Souaid has mostly implicitly rejected the logic of impossible promises to finance. In his view, institutions must make commitments to depositors that they can actually honour. The slowing down of certain decisions would thus ensure their feasibility rather than indefinitely delay the resolution of the crisis.
This caution refers directly to the problem that has blocked the various plans developed since 2020. Recognizing the nominal value of a deposit is one thing. Identifying the liquid assets to repay it in dollars is another.
The real conflict concerns the distribution of losses
For the past seven years, this question has been responsible for much of the blockage. The first government plan developed in 2020 had already recognized the magnitude of the financial sector’s losses. The following governments, the Bank of Lebanon, Parliament, commercial banks and the IMF then diverged on their assessment and, above all, on their distribution.
The debate is particularly sensitive because each option moves the cost to a different category. A massive state contribution amounts to transferring part of the bill to public finances and potentially future taxpayers. The absorption of losses by banks affects their own funds and shareholders. An excessive burden imposed on the Bank of Lebanon can compromise its balance sheet and its ability to maintain monetary stability. A reduction in the claims of depositors directly results in losses to savers.
The banking restructuring adopted in 2026 began to establish a hierarchy. In particular, shareholders must absorb losses before depositors and banks must be assessed individually. But this framework still does not determine the final distribution of the financial hole. This is the expected role of the next law.
This articulation explains the importance of the mission just completed. The IMF no longer negotiates only with Beirut a general list of reforms. Discussions are part of the very mechanics of the distribution of losses.
Depositors remain at the centre of the arm
The issue is all the more sensitive as applicants have already suffered a considerable economic loss since 2019. For several years, book withdrawals at lower market rates resulted in significant discounts. Other depositors sold their bank claims for cash with large losses. Those who have kept their accounts remain subject to restrictions.
Circulars 158 and 166 have improved access to certain amounts, but they are not a general solution to the problem. Their operation remains capped and spread over time. They also do not answer the fundamental question of the final value to be recognized for deposits.
That is why Berry’s assertion of all the deposits will have concrete consequences during the parliamentary examination. If this requirement becomes a principle enshrined in the law, the legislator will have to simultaneously define the assets, deadlines and mechanisms for compliance.
Conversely, a text that formally recognizes claims without providing a credible repayment mechanism could simply prolong the current situation.
IMF wants to prevent depositors from passing over shareholders
The official position expressed by the IMF on its previous mission makes it possible to understand one of the safeguards sought. In February 2026, the institution recalled that no loss should be allocated to depositors until it had been absorbed by shareholders and lower-ranking creditors.
This principle does not mean that the IMF guarantees full repayment of all deposits. It establishes an order in which the losses must be borne. Difference is essential.
The Fund had also warned that the restructuring strategy should remain compatible with the liquidity actually available. Too quickly releasing deposits without the corresponding dollars could create pressure on reserves, exchange rates and financial stability.
The discussion with Beirut is therefore between several requirements: to recognize losses, to protect the hierarchy of creditors, to restore deposits gradually, to recapitalize viable institutions and to avoid the State’s contribution reproducing unsustainable public debt.
A service level agreement as the next step
Yassine Jaber confirmed that the next goal was to get a new service agreement with the IMF. Unlike 2022, the government believes that this time it will be able to introduce several reforms already adopted rather than mere commitments.
However, an ALS would remain an intermediate step. The preconditions established with the Fund would then have to be met before reaching a programme approved by its Board of Directors and providing access to funding.
For Beirut, interest exceeds the amount that could be directly lent by the IMF. An agreement is seen by the authorities as a means of restoring part of the country’s financial credibility and facilitating access to other international financing.
Jaber is expected to continue discussions in Washington during the month. He announced that he would accompany the Prime Minister in meetings with the Managing Director of the IMF and the President of the World Bank. The government hopes to use this sequence to speed up negotiations.
The law will now have to answer a concrete question
The mission from 15 to 18 September therefore failed to reach a final financial agreement. On the other hand, it has tightened the debate on the issue that has been a condition of any lasting exit from the crisis since 2019: how can the accumulated losses be transformed into an architecture that can truly restore deposits?
The positions expressed on Friday already outline the limits of the next parliamentary battle. Nabih Berry requires that depositors’ rights and all their assets be guaranteed. Yassine Jaber claims that the repayment will begin with the adoption of the Financial Gap Act. Karim Suaid announces 8.1 billion dollars returned by the end of 2026 while refusing to promise what the Bank of Lebanon could not finance.
The next meeting will therefore be legislative. The government must move forward on the text while completing the 2027 budget, expected in Parliament in early October. It is in the drafting of this law, then in the amendments to be discussed by the deputies, that the answer still absent on Friday will have to appear: not only how much applicants can recover, but who will actually bring the necessary dollars and how long.