$7,300 a month. The figure immediately hits when it is close to around 2,200 euros corresponding to the median standard of living in France. At first glance, the observation seems to have no appeal: the American household would be more than three times richer than its French equivalent and the gap would continue to widen.
The American figure is correct. It is his comparison with France that poses a problem.
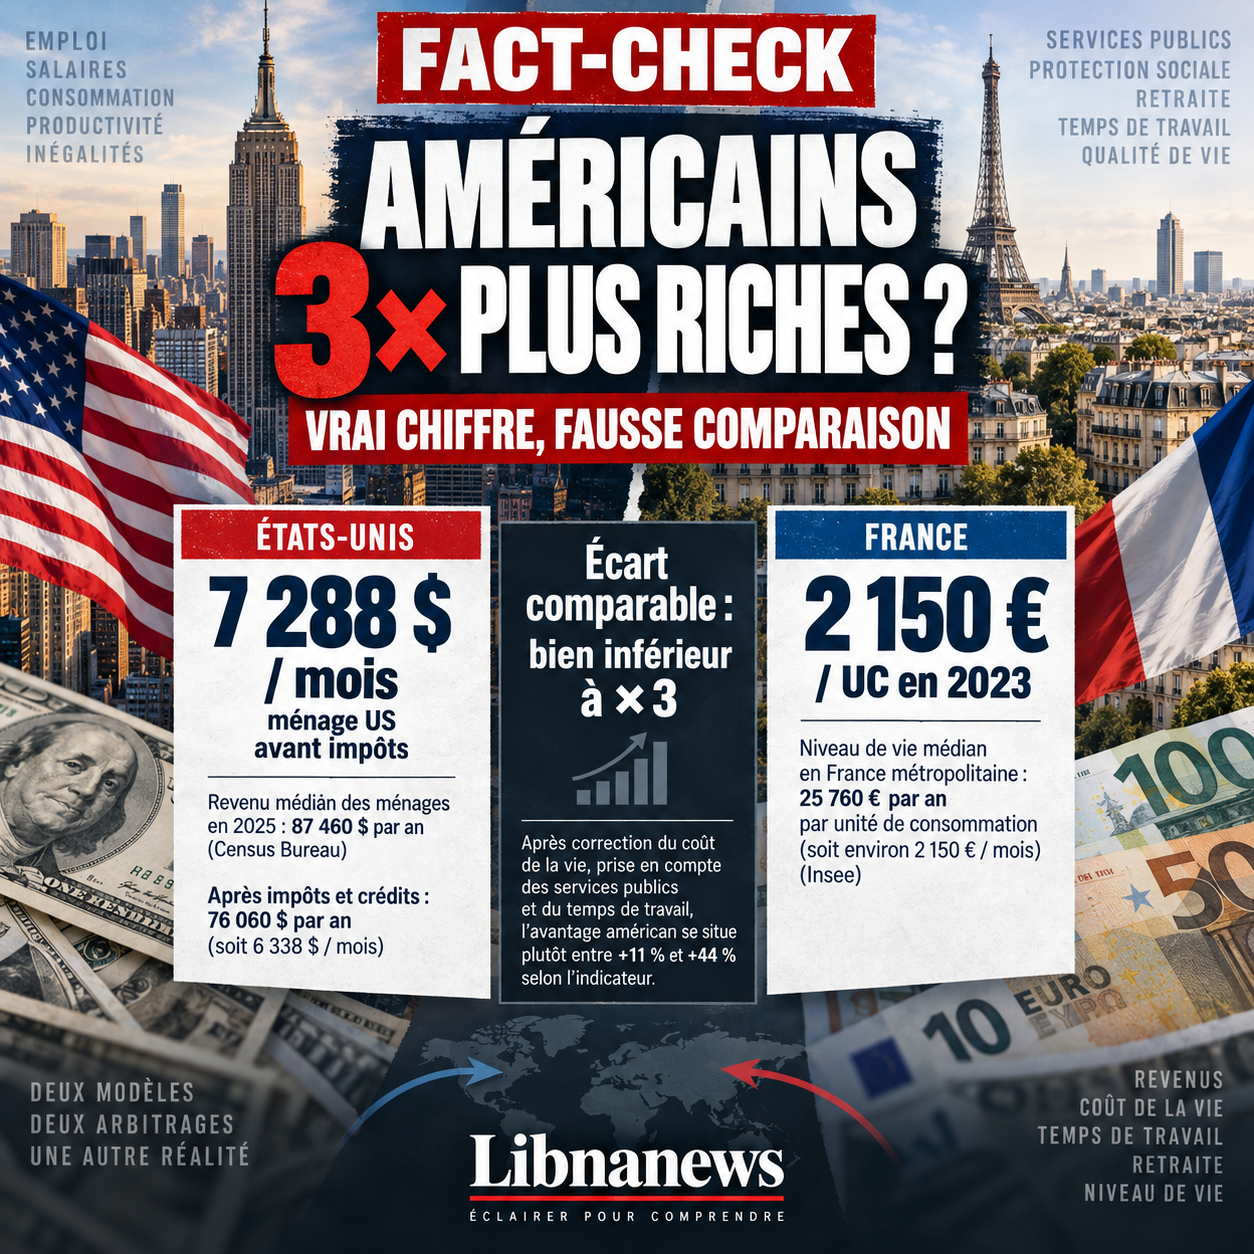
In 2025, the median income of U.S. households was $87,460, or $7,288 per month, according to the latest Census Bureau data. It grew by 2.6 per cent in real terms in one year and reached its highest level since the beginning of this statistic in 1967.
But that $7,288 is neither an American’s salary nor his net income. They correspond to the income of the whole household before taxes. Two working spouses therefore have their income added together.
Once federal and local taxes, salary contributions and tax credits are taken into account, the Census Bureau reduces the U.S. median income to $76,060 per year, or $6,338 per month. Converted at the current exchange rate, the order of magnitude is close to €5,500 monthly.
We are already far from the image of an American household with 7,300 euros net each month.
The French 2,200 Euro Trap
The comparison becomes mainly problematic when you put the approximately 2 200 euros in front of you.
This figure is not the income of the French median household. It corresponds to the median standard of living per unit of consumption: that is, disposable income after taxes and benefits, adjusted for the composition of the household.
A single person represents a consumption unit. A couple represents 1.5 units. A couple with two children under the age of 14 is 2.1.
For example, a family composed of two adults and two young children located exactly at the median French standard of living has about 4,700 euros of disposable income per month.
Comparing US$ 7,300 to US$ 2,200 in France is therefore tantamount to opposing the income before taxes of a whole American household to the standard of living after redistribution corresponding to a single French consumer unit.
The spectacular ratio of more than three to one does not stand up to this first correction.
The French also receives part of their income in another form
Yet there remains a deeper problem. The standard of living depends not only on the money available in the bank account.
In France, a significant part of what could be considered as the economic remuneration of a household has already been converted into health insurance, pension, education, family benefits or social services through contributions and taxes.
These services are obviously not free of charge. They were paid collectively. But once the levies are made, their value disappears from the monetary income comparison.
A U.S. household may have more money but may have to spend a larger part of it on insurance or individual savings to obtain comparable protection.
The United States does not lack social protection. Social Security, Medicare, Medicaid, public education and many federal or local programs represent considerable expenses. Health insurance financed by employers is also a form of remuneration.
The difference lies more in the way this protection is organised: more collective and compulsory in France, more divided between the State, employer and private schemes in the United States.
When public services are counted, the gap goes down
The OECD has an indicator to correct this problem: adjusted disposable income. It adds to monetary income the value of individualizable services received by households, particularly in health, education and social action.
By also correcting price differences between the two countries through purchasing power parities, the comparable data for 2023 give around PPP$51,100 per capita in France compared with US$68,250.
The U.S. advantage remains significant: about 34%.
But it is no more than 227%.
Another measure, effective individual consumption, which seeks to measure all goods and services actually consumed independently of those that finance them, leads to a larger US advantage, close to 44%.
If France is worth 100, then the United States is around 144.
The Americans are on average much richer. The statistical correction does not remove the gap. It radically changes its size.
An American average drawn upwards
However, one problem remains: these 34% or 44% are based on averages.
But American society is significantly more unequal than French society.
This means that a national average less accurately describes the situation of the household in the middle of the distribution. The incomes and consumption of the wealthiest households are more averaged upwards in the United States.
The latest US data also illustrate this. By 2025, the income of the 90th percentile increased by 1.7%, while no statistically significant increase was recorded at the 10th percentile.
This mainly prohibits a conclusion often drawn too quickly from the average statistics: saying that American consumption is 44% higher does not mean that the median American lives 44% better than the median French.
Available data on median income in purchasing power parity show a much smaller difference than in averages. The United States remains ahead, but the gap in the middle of the distribution is significantly lower than that given by average consumption.
There is, however, no recent series for obtaining directly and using the same methodology a « median adjusted disposable income » simultaneously integrating social transfers in kind and PPPs for both countries. Artificially assigning a precise figure of 20%, 25% or 30% to this difference would therefore give an accuracy that the available statistics do not allow.
Americans also work much more
Finally, there is a wealth that hardly ever appears in these comparisons: time.
OECD data put the annual volume of work around 1,500 hours per worker in France, compared with about 1,800 hours in the United States.
This represents about 20% extra work per year for an American worker.
The difference is the result of a number of factors: weekly duration, part-time work, leave, organization of the labour market. But its magnitude changes the reading of income differences.
An American who consumes more but also works more does not get free of charge all his standard of living supplement.
The contrast on leave is particularly telling. French legislation guarantees five weeks of paid leave. In the United States, there is no general federal legislation requiring a private employer to offer paid annual leave, even though a large proportion of employees benefit through their company.
And per hour of work, the gap is further reduced
This is probably one of the most instructive corrections.
The U.S. actual individual consumption is about 44% higher than that of France in the data used: for a France reduced to 100, the U.S. is around 144.
But the American worker spends about 1,800 hours a year against 1,500 for his French counterpart.
If, as an illustration, these two quantities are reported at the time worked, the result changes sharply.
A France reduced to 100 then gives the United States around 120.
In other words, the U.S. advantage of about 44% of average effective consumption per capita falls to around20% when related to the working time differential.
The calculation is even more spectacular with adjusted disposable income.
We had an American advantage of about 34%, social services in kind and price differences included. By also reporting this difference to the approximately 20% of overtime worked in the United States, the benefit falls around11%.
These two calculations are not official OECD indicators. They approximate the series whose reference populations are not exactly the same: consumption and adjusted income are measured per capita, while the number of hours concerns workers.
They therefore do not make it possible to say that an American enjoys exactly 11% or 20% additional standard of living per hour worked.
But they highlight a reality that the income comparison completely ignores: a significant part of the US material advantage is achieved by devoting more time to work.
Work More, and Longer
The difference does not stop with the year of work. It continues until retirement.
In OECD simulations of future retirees, the normal age used is 65 in France compared to 67 in the United States.
The difference is even more interesting when you look at what the employee then receives.
For a person who has earned the average salary for a full career, the OECD estimates the future net replacement rate for compulsory schemes at 70% in France compared with 51.3% in the United States.
The American can of course greatly improve his retirement with a 401(k), an IRA, a business pension or his financial assets. But that money must have been saved before.
A portion of the additional US income is therefore used individually as a protection that the French employee finances more through compulsory levies during his career.
Again, the immediately available income tells only part of the story.
Over an entire career, the time gap becomes considerable
The approximately 300 hours of annual difference do not represent just a few weeks of extra work over a year. They accumulate for several decades.
In purely illustrative terms, assuming an entry into working life at the age of 22 and applying the current annual volumes of work to a full career, a Frenchman working up to the age of 65 would accumulate approximately 64,000 hours of work.
An American working up to 67 years, with about 1,800 hours per year, would approach 81,000 hours.
The difference would then be of the order of17,000 hours in a career, or about27% additional working time.
This simulation obviously does not describe any real individual careers. Annual hours will change, periods of unemployment or part-time work differ and all employees do not start or end their careers at the same age.
But it makes it possible to visualize the dimension of the phenomenon: the American advantage in income and consumption is also accompanied by a significantly higher investment in working time over the entire working life.
Two years of retirement also have a value
The reasoning must even be extended after working life.
Two additional years of retirement do not generate any wage income or increase GDP. Yet they constitute two years of available time.
The French model therefore does not only transform part of the wealth produced into health, education or collective retirement. It also turns a part of it into off-duty time.
This dimension is difficult to monetize. How much is an hour of leisure? Should it be valued at the hourly wage, at a fraction of it or according to individual preferences?
There is no universal response.
That is precisely why it would be excessive to proceed mechanically with our calculation and to say that, after valuing time, the American advantage would be only 5%, or that it would disappear completely.
The data do not permit such accuracy.
On the other hand, they show that only comparing incomes necessarily overestimates the welfare gap when one of the two countries works significantly more.
Two models rather than a ratio of three to one
The initial comparison suggested something very simple: $7,300 against approximately $2,200.
After examination, almost every element of this comparison must be corrected.
The $7,300 is the pre-tax income of the entire U.S. household. After taxation, they become $6,338. The approximately 2 200 euros in French do not correspond to the income of a household but to a unit of consumption after redistribution. The price differences must then be corrected and the value of public and social services received in each country must be incorporated.
At this stage, the average U.S. advantage is more in the range of 34-44% according to the chosen indicator than in the 227% implied by the initial comparison.
And these 34-44% are still averages in a much more unequal American society.
Finally, the American works about 20% of the overtime per year and, in OECD pension projections, works longer to benefit from a less generous compulsory pension, except to supplement it with personal savings.
When compared to working time, our exercise reduces the US advantage to about20 % for actual consumptionand about11% for adjusted disposable income. These orders of magnitude are not an official measure of well-being, but they show how the perception of the difference changes when time enters the calculation.
Verdict: real number, false comparison
American households are richer than French households. Their disposable income and material consumption remain higher even after adjusting for the cost of living and taking into account public services.
France’s relative stall against the United States is therefore an economic reality which it would be equally misleading to deny.
But the $7,300 monthly does not show that an American household has three times the standard of living of a French household.
They measure the income before tax of an entire American household.
The really interesting comparison contrasts rather two economic arbitrations. The United States provides more income and consumption, at the cost of higher working hours, longer careers, stronger inequalities and greater individualisation of certain social risks. France provides less material consumption but transforms more wealth into collective protection, retirement and time off work.
The shift from gross to comparable indicators gives an indication of the magnitude of the correction: the initial impression of an American advantage of more than 200 % falls to about 34-44% when the PPP is used and social services are taken into account. The median household gap is likely lower due to American inequalities. And when these average indicators are related to the working time differential, the order of magnitude falls around 11 to 20% depending on the measure used, before even giving a value to the additional retirement years and leisure time.
In other words, the gap exists. But it is much less spectacular than a figure of $7,300 from its context.