The draft law intended to organize the treatment of financial losses and the reimbursement of Lebanese depositors advances in a much less linear way than the public debate suggests. Behind known disagreements over the distribution of losses between the State, the Bank of Lebanon, banks and their shareholders, Annahar of 16 September 2026 describes an unusual legislative process: remarks attributed to the International Monetary Fund would continue to arrive even as the texts are already under discussion, forcing Lebanese officials to take over provisions already discussed.
This mechanism would directly contribute to delays. It also provides a better understanding of why the Governor of the Bank of Lebanon, Karim Suaid, does not expect a speedy adoption of the text on financial organization and return of deposits.
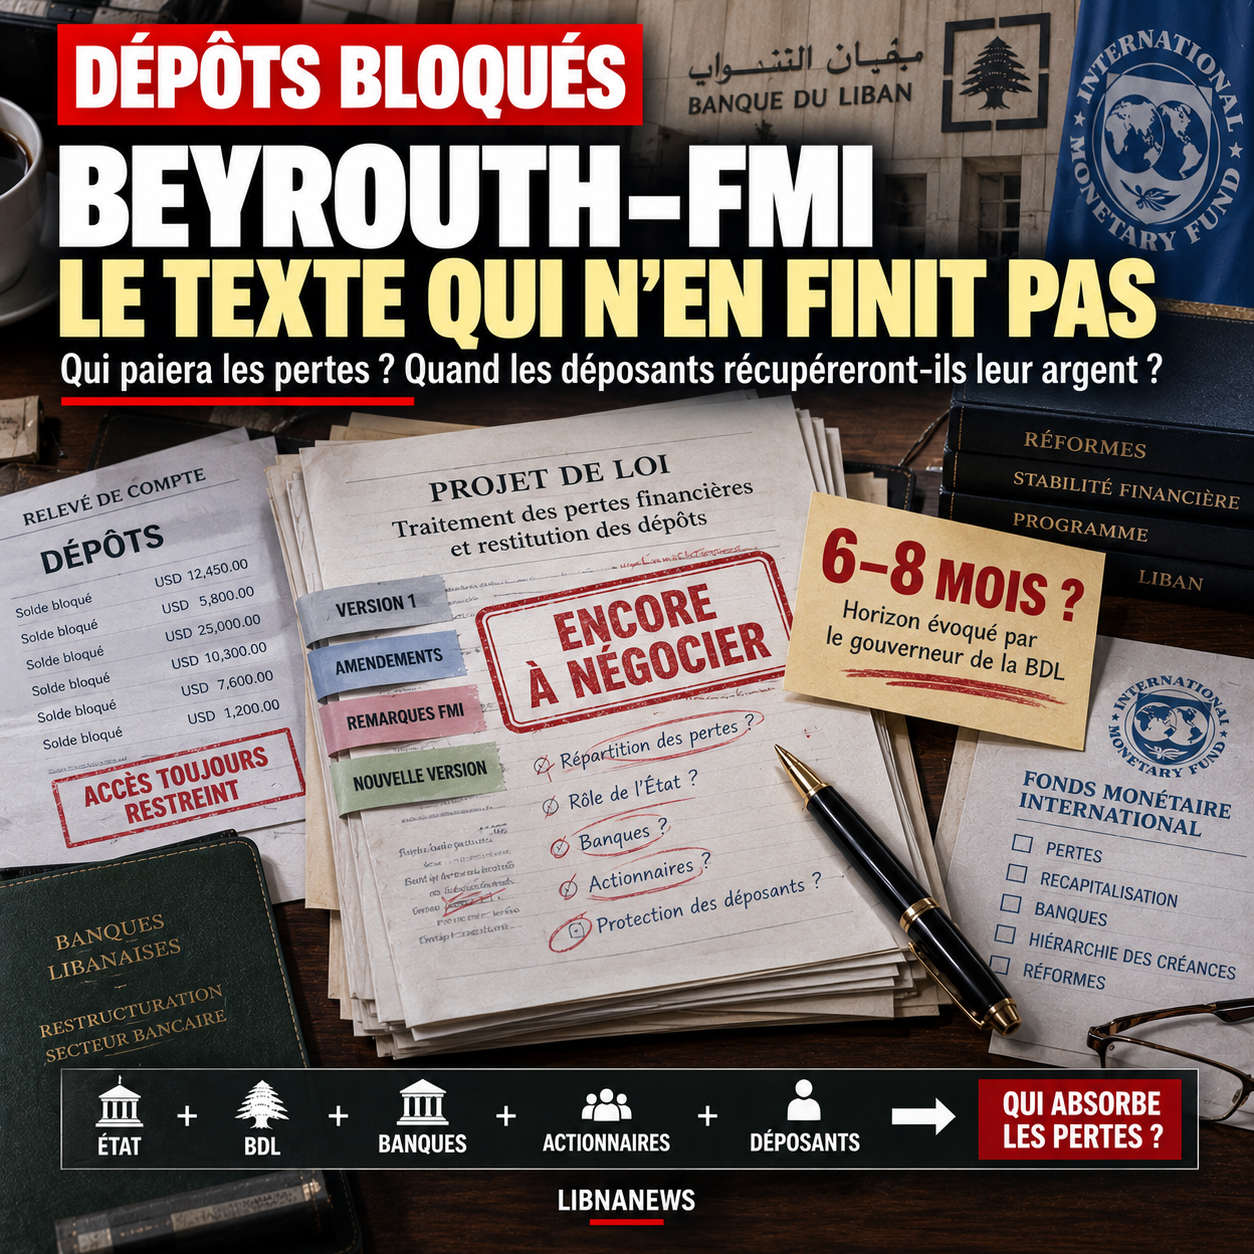
According to Annahar, Karim Souaid recently mentioned a horizon of up to eight months before the project was adopted. The daily newspaper states that this estimate was not necessarily a criticism to Parliament. It would focus on how the financial texts negotiated with the Fund were developed, amended and reviewed.
The subject is particularly sensitive. This project must determine the rules for dealing with part of the consequences of the banking crisis that deprived depositors of normal access to their money. It must also complement the legislation already adopted on banking restructuring. However, according to the information published by Annahar, the text has still not reached a sufficiently stable form to allow for an ordinary parliamentary journey.
Changes coming after the start of parliamentary work
Annahar’s most interesting confidence concerns the circulation of the Monetary Fund’s remarks.
The newspaper explains that, in a traditional legislative process, the Council of Ministers adopts a draft and forwards it to Parliament. The parliamentary committees then examine it before it passes before the assembly.
In the texts related to the financial reform programme, the functioning would be different.
According to Annahar of 16 September, once the draft has been transmitted to Parliament and its consideration has begun, new lists of comments and changes attributed to the Monetary Fund could still reach Lebanese officials.
The parliamentary committee would then be faced with a moving text.
Certain provisions already discussed should be reopened. In some cases, the review might even concern articles on which a vote had already taken place.
The problem is therefore not only the existence of differences between Lebanon and the Fund. It is due to the moment when these differences appear in the process.
A text considered sufficiently successful to be forwarded to Parliament could continue to evolve after its arrival before Members.
Annahar believes that this method has already contributed to considerably prolonging the examination of previous financial reforms.
Comments from unusual circuits
The daily life reveals another much more surprising detail.
According to Annahar of 16 September, there would be no direct formal correspondence between the Monetary Fund and Parliament in this process.
Some remarks would come through the government or advisers. The newspaper even evokes transmissions by instant messaging or by e-mail that would not take the form of traditional institutional correspondence with Parliament.
This information deserves to be handled accurately. Annahar does not say that Lebanese laws are drafted directly by the Monetary Fund. It describes a mechanism in which observations attributed to the international institution reach those responsible while the legislative procedure is already under way.
But this method raises an obvious institutional question: when does a project negotiated with an international organization become definitive enough to be passed on to the legislator?
The problem is all the more important because the changes are not marginal.
Annahar recalls that, during the review of the Banking Restructuring Act, comments received during the course of the project could have concerned a significant part of the text.
The commission had to come back to its own work.
The government would have taken over the text
Moreover, the draft on the financial deficit and deposits would no longer simply be in Parliament’s hands.
Annahar reports that Nawaf Salam would have taken over the project for reconsideration.
This movement partly explains why Karim Suaid does not consider his adoption imminent.
So the question is not just how long Parliament will take to vote on the law. A sufficiently stable version must first be achieved between the government, the financial authorities and the Monetary Fund.
However, the differences remain significant.
The visit to Beirut by a delegation from the Fund is precisely in this context. The project on financial organization and deposit return is one of the main issues discussed.
The central point of friction remains the way in which the losses accumulated since the crisis will be absorbed.
Who will pay the bill?
Behind the technical discussions is a simple and politically explosive question: who will bear the losses?
The State may be called upon to assume part of the burden. The Bank of Lebanon is directly affected by the scale of its balance sheet and the liabilities accumulated in the years preceding the crisis. Commercial banks are also at the centre of the scheme. The fate of their shareholders and capital is one of the sensitive points of the negotiations.
Finally come the depositors.
Any financial architecture is judged in Lebanon through a question: what part of their deposits will they be able to recover, according to what timetable and in what form?
Annahar indicated that discussions with the Fund included mechanisms for the allocation of losses and restructuring and recapitalization of banks.
The project must therefore arbitrate between directly contradictory interests.
Too much loss to depositors would be politically difficult and socially heavy. Putting the burden on the State amounts to transferring it to public finances and thus ultimately to taxpayers. Imposing massive recapitalisation on banks can lead to the disappearance or restructuring of part of the sector.
There is no cost-free solution.
That is precisely why every modification of the text causes a new battle.
Karim Souaid does not believe in rapid adoption
In this context, the estimate of the Governor of the Bank of Lebanon takes on another meaning.
According to Annahar, Karim Suaid indicated that the law might not come into being for several months. The newspaper insists that this assessment does not necessarily aim at the pace of Parliament’s work.
Instead, the Governor would have taken into account the whole process: negotiations, amendments, government arbitrations, Fund remarks, committee review and then parliamentary adoption.
The difference is important.
Just accusing Members of delaying the reforms would not make it possible to explain why the projects come before them before they are still undergoing substantial changes.
Annahar estimates that this method can add six to eight months to a text.
The responsibility for delay therefore becomes diffuse.
The government is negotiating. The Fund makes requirements or observations. Parliament is considering. Financial authorities intervene. Then some arrangements go back to the circuit.
Meanwhile, the depositors are waiting.
A battle around the article on banks
The disagreement relates in particular to the conditions imposed on the banking sector.
Annahar reports that discussions remain difficult on the mechanism of recapitalisation and balance sheet clearance. The stated objective is to determine which banks are able to regain a viable financial position and which will have to be restructured or out of the market.
This step is inseparable from the processing of deposits.
A bank cannot be declared viable without determining the real value of its assets, losses and liabilities that it can still honour.
Since the beginning of the crisis, the Fund has emphasized the need to recognize losses rather than delay them indefinitely.
But sharing these losses remains the core of the Lebanese conflict.
Each actor seeks to reduce its share.
Banks defend their survival and shareholders. The State seeks to avoid further burdening its finances. The Bank of Lebanon must preserve its future ability to conduct monetary policy. Depositors demand the return of their assets.
The law must turn this conflict into rules.
That is precisely what explains his difficulty.
The Fund, an indispensable but disputed partner
The relationship with the Monetary Fund therefore remains ambivalent.
Lebanon needs an international agreement to restore part of its financial credibility and facilitate access to external financing. The Fund is seeking a series of reforms to make the financial system sustainable.
But the way these requirements enter the national procedure itself becomes a subject.
The information published by Annahar highlights an area that is not visible in the process: the movement of changes between international experts, the government and parliamentarians.
If the comments continue to arrive after the official transmission of the drafts, the debate no longer focuses solely on their content. It also concerns the method used to produce the law.
This issue is far from secondary.
A reform as important as that of deposits must determine the fate of part of the savings accumulated by the Lebanese for decades. It will also re-design the banking sector and determine the distribution of a considerable share of financial losses.
The legal stability of the text is therefore essential.
On the contrary, Annahar describes a process where the project can continue to change while its review is already underway.
Eight months that could still be expensive for applicants
The horizon mentioned by Karim Souaid does not mean that the law will necessarily be passed in eight months. Rather, it gives an idea of how long the process can take if current differences persist.
None of the published information yet makes it possible to obtain the final version of the text.
Nor is it possible to determine precisely what each category of applicants will recover. The final modalities remain dependent on the arbitrations which still have to take place.
This is precisely what makes Annahar’s confidences important.
They show that, behind the public statements on the urgency of the reforms, the law most expected by Lebanese applicants continues to be negotiated at several levels. And that the text submitted to MEPs tomorrow may not be exactly the one circulating between Beirut and the Monetary Fund today.
For depositors, the institutional debate has a very concrete consequence: as long as Lebanese officials and the Fund have not stabilized their compromise on losses, banks and deposits, the return schedule will also remain suspended.