

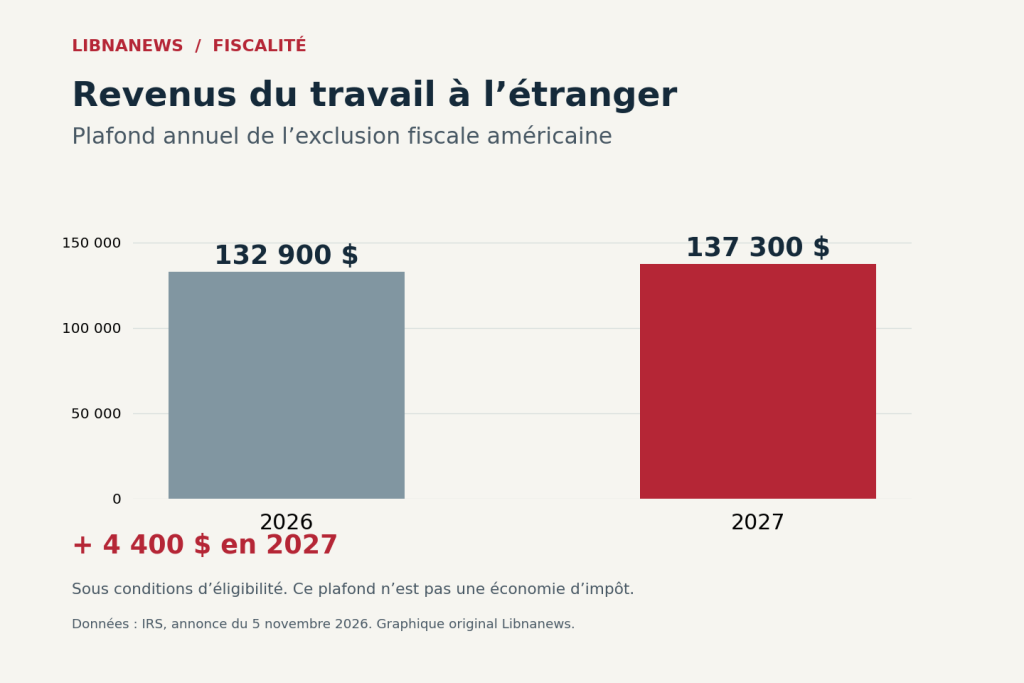
US 2027 taxes are becoming more precise. On November 5, 2026, the federal tax administration announced that nearly 70 provisions would be adjusted annually. The thresholds of the instalments, the lump sum deduction and several credits increase. For U.S. taxpayers working abroad, the cap on excluding business income will reach $137,300, compared to $132,900 in 2026. These amounts generally relate to declarations filed in 2028.
The announcement is of interest to households in the United States, particularly in the Lebanese diaspora. It also concerns some American citizens living in Lebanon or in another country. Their residence abroad does not alone remove their US tax obligations. However, the application of the measures depends on the tax status, the nature of the income and the conditions of each benefit.
The update is based on annual inflation indexation. It intervenes within the existing legal framework. The publication of 5 November is therefore not a new reform voted after the American elections. It sets usable amounts for fiscal year 2027, with income tax rates that remain between 10% and 37%.
US taxes 2027: the calendar to be distinguished
Three dates may be confusing. The announcement came in November 2026. The new thresholds relate to revenues for fiscal year 2027. The corresponding declarations will generally be filed in 2028. The spring 2027 reporting campaign will concern the revenues of 2026.
This lag counts to compare the scales. A household preparing its next return should not replace the 2026 thresholds with those announced for 2027. Similarly, the increase in a ceiling for next year does not retroactively change a return already filed. The year of income remains the first benchmark to be verified.
A lump sum deduction of $33,200 for a couple
For married couples filing a joint declaration, the lump sum deduction will reach $33,200 in 2027. It increases by $1,000 over 2026. For single and married individuals reporting separately, it will be $16,600. The amount applicable to the United States « head of household » category will be $24,925.
This category corresponds to a tax status subject to specific conditions. It is not simply derived from being the person who finances a home. The amounts announced are the basic deductions. Certain situations, such as age or blindness, may qualify for additional amounts.
A deduction reduces income for tax purposes. It is not an amount paid to the taxpayer. Thus, the $1,000 increase for a joint statement does not announce an automatic repayment of $1,000. Its effect depends in particular on taxable income and other elements of the declaration.
The seven rates remain in place, the thresholds change
The federal scale retains seven marginal rates. The following thresholds apply to taxable income after the applicable deductions. They must not be read as gross wage levels.
| Marginal rate | Single: taxable income | Married couple, joint declaration |
|---|---|---|
| 10 % | Up to $12,800 | Up to $25,600 |
| 12 % | Over $12,800 | Over $25,600 |
| 22% | Over $52,025 | Over $104,050 |
| 24 per cent | Over $109,125 | Over $218,250 |
| 32 % | Over $208,325 | Over $416,650 |
| 35 % | Beyond $264,550 | Over $529,100 |
| 37% | Over $661,375 | Beyond $793,650 |
Each rate applies to the income portion of its band up to the next threshold. Crossing a threshold therefore does not subject all income to the higher rate. The marginal rate differs from the average rate actually supported. This table does not cover other reporting statuses or special schemes for certain income.
Abroad, an exclusion of $137,300
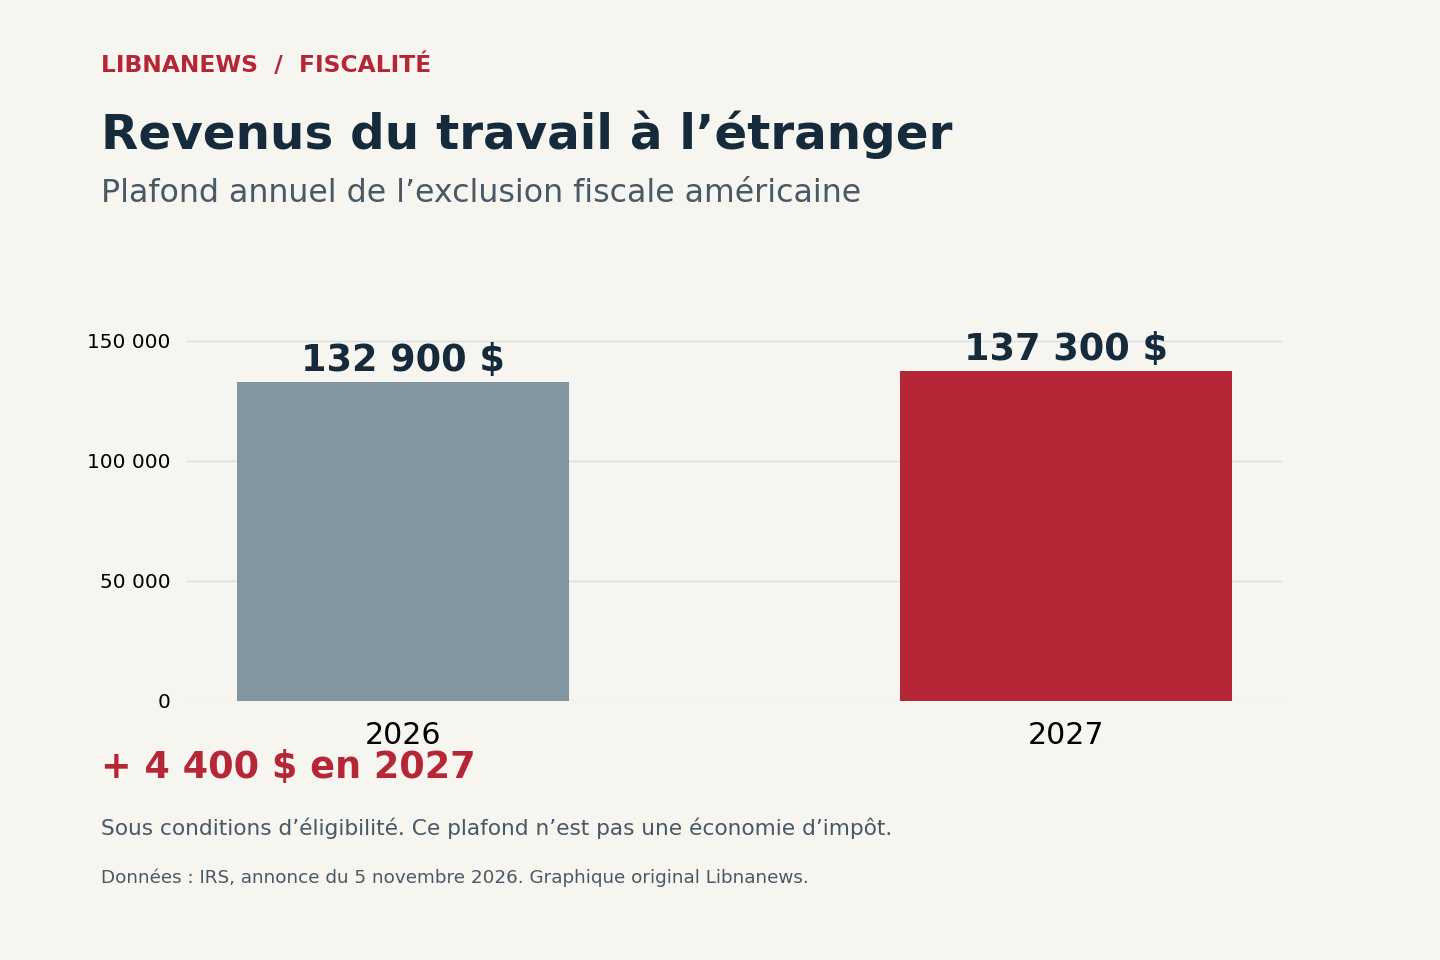
The annual ceiling for the foreign earned income exclusion is increased from $132,900 to $137,300. The increase is $4,400. This scheme allows, subject to conditions, to exclude foreign professional income from the calculation of federal income tax. This is neither a payment nor a general exemption from all resources received outside the United States.
In order to qualify, foreign professional income and a business tax domicile in a foreign country are required. The rules then provide for different tests. In particular, a U.S. citizen may meet the criterion of actual residence abroad for an uninterrupted period of time including an entire fiscal year.
Another route is a physical presence abroad of at least 330 full days for 12 consecutive months. The conditions applicable to U.S. tax residents who are not U.S. citizens are unique. Therefore, the mere fact of owning or staying in Lebanon does not make it possible to conclude eligibility.
The nature of the amounts received remains decisive. The scheme covers income from work, such as wages or fees. Pensions and annuities do not fall within this definition. For eligible self-employed workers, exclusion can reduce income tax without reducing the US self-employment tax.
For an American citizen living in Lebanon, the new ceiling can thus be of practical scope. But it does not automatically exempt from filing an American declaration. Global revenues are in principle still affected by the US tax system. The available benefits must be claimed in the appropriate declaration.
Child credit increases by $100
The maximum child tax credit will reach $2,300 in 2027, compared to $2,200 in 2026. The refundable share will increase to $1,800, or an additional $100. These ceilings do not guarantee that each family will receive the maximum amount. Eligibility and calculation remain subject to the credit rules.
The difference with the lump sum deduction is essential. A credit affects the tax calculated, while a deduction affects taxable income. The refundable nature answers another question: the possibility of receiving part of the credit beyond the tax due. Adding all the announced ceilings directly does not therefore save a household’s tax burden.
Taxpayers with income or attachments in several countries will also have to review their separate reporting obligations. Certain foreign account returns remain due even in the absence of taxable income from these accounts. The upgrading of the income ceiling does not remove them.
The amounts published are now the federal benchmarks for 2027. Their application to an individual situation requires verification of the declaratory status and conditions of each device. Any future legislative changes could lead to new instructions before filing 2028 returns.





Comments