Remove deposits from face-to-face between banks and savers
The bank deposit file may change in nature. After years in which it was treated as the heart of the Lebanese financial crisis, reflections in the documents studied are now part of a much larger project of state reconstruction. Reimbursement of savers would no longer be merely an operation designed to offset the consequences of the banking collapse. It would become an instrument to restore confidence in institutions, bring capital back into the financial system and accompany the country’s economic transformation. This approach places depositors at the same strategic level as the reconstruction of the South, the strengthening of the army, administrative reform and the restoration of financial sovereignty.
Change is important. Since the crisis, the Lebanese debate has focused on a central question: who should bear the accumulated losses? The State, the Bank of Lebanon, commercial banks, their shareholders or depositors? The responses so far have not restored a normal relationship between citizens and financial institutions. Savers have seen their money blocked or subjected to restrictive withdrawal mechanisms. At the same time, the economy has adapted. Physical dollars have taken on a significant role, cash payments have become widespread and a significant part of transactions have moved away from banks.
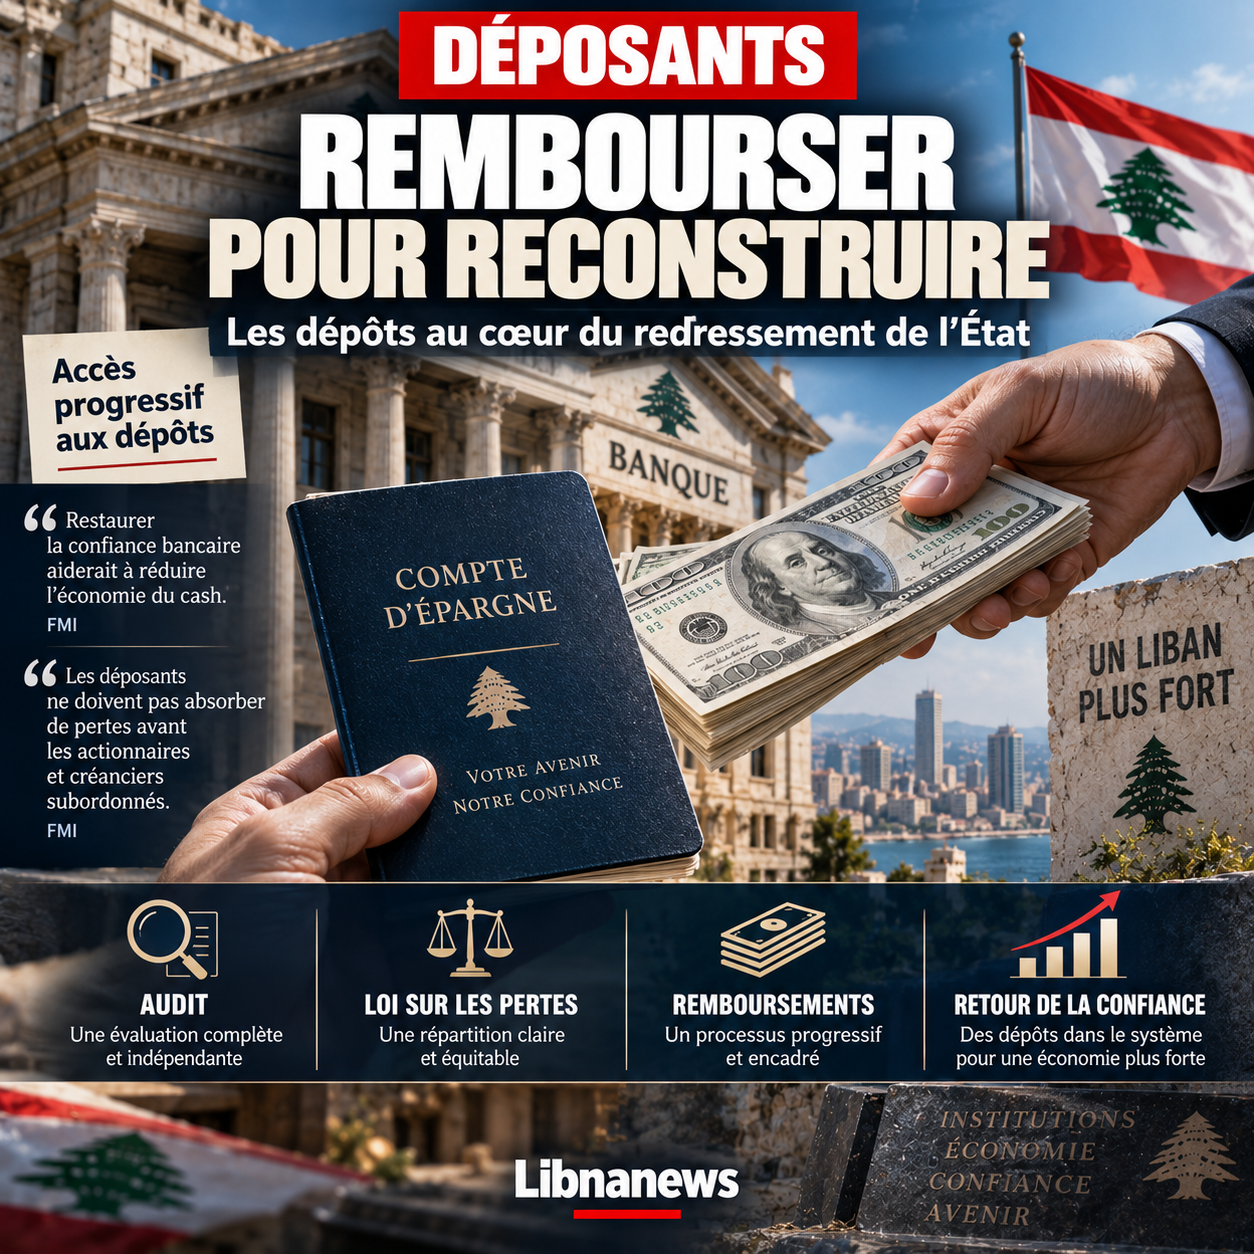
The new approach seeks to reverse this dynamic. It is based on a simple idea: no lasting reconstruction of the financial system is possible if depositors remain convinced that investing money in a bank is a risk. The gradual recovery of deposits becomes not only a question of financial justice, but a condition for the return to normal economic functioning.
A full audit before determining who should pay
The first stage envisaged would be an in-depth and independent audit of the Bank of Lebanon and commercial banks. It would not simply be a matter of updating a few reviews. The objective would be to establish commitments, losses and responsibilities precisely before determining how they should be distributed.
This is a fundamental step. A durable solution cannot be based on disputed figures or a political estimate of losses. There is a need to determine the actual situation of institutions, identify the assets available and measure the ability of everyone to participate in the reorganization. The envisaged process should meet criteria consistent with those of the International Monetary Fund and be entrusted to a structure with international credibility.
The timetable for the audit and legislative changes would cover a period of six to twelve months. This duration shows that the project does not provide for an instant return of all deposits. Rather, it seeks to build a mechanism to start repayments while restructuring the sector.
The challenge will also be to prevent the audit from becoming a new exercise without consequence. Lebanon has already had many discussions on loss valuation, restructuring and liability. The difference would this time lie in the direct link between the audit, a loss allocation law and the effective triggering of refunds.
A law to allocate losses
The second stage would be legislative. The distribution of losses should be determined by legislation passed in Parliament. This provision is essential because it would, in principle, prevent the treatment of one of the largest financial crises in the country’s history from being settled only by administrative decisions or by agreements between institutions.
The law should define the respective responsibilities of the State, the Bank of Lebanon and commercial banks. It should also determine how shareholders would participate in the absorption of losses. Above all, it should provide special protection for small and medium-sized applicants.
This last point is one of the clearest guidelines of the proposed scheme. Not all applicants would be treated equally. Priority would be given to those whose savings represent a family heritage or the product of a working life, rather than much larger capital.
However, the available documents do not provide a complete schedule to determine precisely the amount that would define a small, medium or large depositor. They also do not permit the determination of the exact proportion of deposits to be repaid to each category. These elements should be set out in the legislative and financial framework. Presenting specific thresholds today would therefore go beyond what the sources suggest.
First repayments in the first year
The timetable envisaged is ambitious. After the audit and legislative preparation phase, first repayments are expected to begin in the first year. The restoration of complete solvency would then be included in a programme of up to five years.
This temporality responds to both political and financial logic. Waiting several years before paying the first dollar to the depositors could condemn the project as soon as it was launched. To regain credibility, the state must quickly produce a visible result.
The initial reimbursement would thus have a symbolic function. It would show that the process is not to produce new legislation or announce a new plan. It would provide savers with proof that restitution has actually begun.
But this speed creates a major difficulty: where will the money come from? A promise of repayment is of value only if the sources of financing are identified. The documents studied give a general architecture, but they do not allow for a definitive table of available liquidity year after year. The audit therefore becomes indispensable precisely because it has to determine what each actor can actually support.
Bank of Lebanon’s gold as a guarantee of confidence, not as a crate to empty
The question of gold reserves is also reflected in the considerations studied. However, their role would be very different from that sometimes imagined in the public debate. Gold would not be considered as a reserve for immediate sale to reimburse applicants.
Rather, it would serve as a basis of confidence for rebuilding the country’s financial credibility. The aim would be to preserve this asset rather than sell it, pawn it or increase new bonds without control.
Any use of gold should also require explicit authorisation from Parliament. This requirement introduces an institutional lock. Such an important national asset could not be mobilized simply by administrative decision.
This caution is a clear problem. Using gold reserves to cover losses immediately could provide liquidity, but would not resolve the causes of the crisis. Once the country has consumed its assets, it would still face a weakened banking system if structural reforms were not implemented. The philosophy is therefore to use the existence of gold as a credibility factor rather than as an immediate budgetary solution.
Repayment as a means of combating the cash economy
The strategic interest of the case appears especially when it is close to the evolution of the Lebanese economy since the crisis. Mistrust of banks has led to widespread cash transactions. For many households and businesses, keeping physical dollars has become a rational behavior after the experience of blocked deposits.
This situation, however, complicates economic reconstruction. Banks have fewer resources. Credit remains limited. Transactions are harder to trace. The authorities have reduced visibility on part of the financial movements. Finally, international partners are concerned about the possibility of money laundering and financing of sanctioned networks.
Reimbursement of depositors becomes a means of reversing this logic. If a saver finds that his money is gradually being returned to him and that the new rules better protect his rights, he can start to consider the bank again as a normal tool.
However, the return of deposits will not be automatic. It will require more than a first refund. Depositors will have to be convinced that the new funds they place in banks will not suffer the fate of the old ones. This implies a clear separation between the treatment of liabilities inherited from the crisis and the operation of new deposits.
A bank reconstruction that would change the institutional landscape
The audit and the allocation of losses will necessarily have consequences for the banks themselves. Not all have the same financial situation. Some might be able to recapitalize and continue their activity. Others may have to merge or be restructured. Establishments unable to meet the new requirements could disappear in their current form.
The project cannot therefore be understood as a plan to save all banks without distinction. The priority displayed concerns the restoration of the system and the protection of applicants, not the preservation of each establishment.
Restructuring must also create a smaller but stronger sector. After such a crisis, artificially maintaining insolvent institutions would only push the problem back. On the other hand, the abrupt closure of establishments without a protection mechanism could worsen the losses of savers.
The balance will be difficult. Surviving banks will have to meet stronger capitalization, governance and compliance requirements. They will also have to convince their foreign correspondents that control mechanisms have changed.
A political dimension that goes far beyond finance
The applicants’ file becomes even more sensitive when integrated into the broader reconstruction programme referred to in the documents. It combines banking recovery, reconstruction of war-affected areas, digital government, military strengthening and the return of state authority.
In this architecture, making money to depositors produces a political effect. During the crisis, the State’s inability to protect savings has severely weakened its credibility. Restoring financial rights therefore becomes a way of restoring institutional authority.
The logic is comparable to that envisaged for the reconstruction of the South. When the State directly provides a service, finances a reconstruction or protects a deposit, it reduces the citizen’s dependence on political, community or private intermediaries.
The project thus goes beyond the framework of a bank plan. It seeks to rebuild the link between citizen and institution. This ambition explains why applicants occupy such an important place in a strategy that simultaneously deals with security, sovereignty and reconstruction.
The risk of turning a financial promise into a political instrument
However, this architecture is dangerous. The more the repayment of depositors is integrated into an international transformation strategy in Lebanon, the more likely it is to be perceived as conditional on political objectives.
Some people may fear that access to the necessary funding will depend on decisions taken on other issues, including security, Hezbollah weapons or relations with Israel. The documents studied establish strategic links between these different projects, but they do not permit the assertion that the individual reimbursement of an applicant would be legally conditional upon a safe decision.
Distinction is essential. An international programme may combine several reforms in the same strategy without any formal payment being subject to all other measures. The article must therefore avoid presenting as a legal condition what is, at this stage, a general political architecture.
However, this ambiguity could become a source of conflict. The depositors have been waiting for their money for years. They could refuse to use their situation as a lever in broader political negotiations. Conversely, donors may consider that they should not commit significant resources without guarantees of reform.
Who will control the money?
The problem of governance is therefore central. Recovery-related funding should be combined with reform indicators and mechanisms to prevent resource capture. This requirement meets the accumulated mistrust of public and banking management.
The digital transformation envisaged in the general programme could also concern the monitoring of payments. The aim would be to reduce intermediaries, identify beneficiaries and allow more accurate control of flows.
For applicants, such an architecture could make repayments more transparent. It would provide information on which categories were paid, on which timetable and on what legal basis. It would also limit the risk of preferential treatment being given to certain actors.
But transparency must begin before repayments. The allocation of losses itself must be understandable. Without the publication of calculation methods and responsibilities, citizens risk seeing the mechanism as another attempt to make them bear losses decided elsewhere.
The real test will be the voluntary return of money to banks
Success cannot ultimately be measured solely by the amount reimbursed. The best indicator will be the behaviour of Lebanese after the first payments.
If the depositors recover part of their funds and immediately keep them in cash at home or transfer them abroad, the return will have responded to a legitimate request but will not have restored the financial system. If, on the contrary, some savers resume using banks, the mechanism will have produced a much deeper effect.
In order to achieve this result, the authorities will have to establish a clear border between the old system and the new one. Citizens must be aware that new deposits are protected by different rules, that surviving banks have sufficient capital and that controls prevent the recurrence of practices leading to collapse.
It is on this condition that the file of the applicants can become a true piece of the reconstruction of the State. The return of savings would not only result in debt to hundreds of thousands of people. It would bring capital back to institutional channels, reduce the cash economy, restore credit and make financial control more effective. After years when the banking crisis symbolized public impotence, the repayment of depositors could thus become one of the most concrete tests of Lebanon’s ability to rebuild a relationship of trust between the state, banks and citizens.