
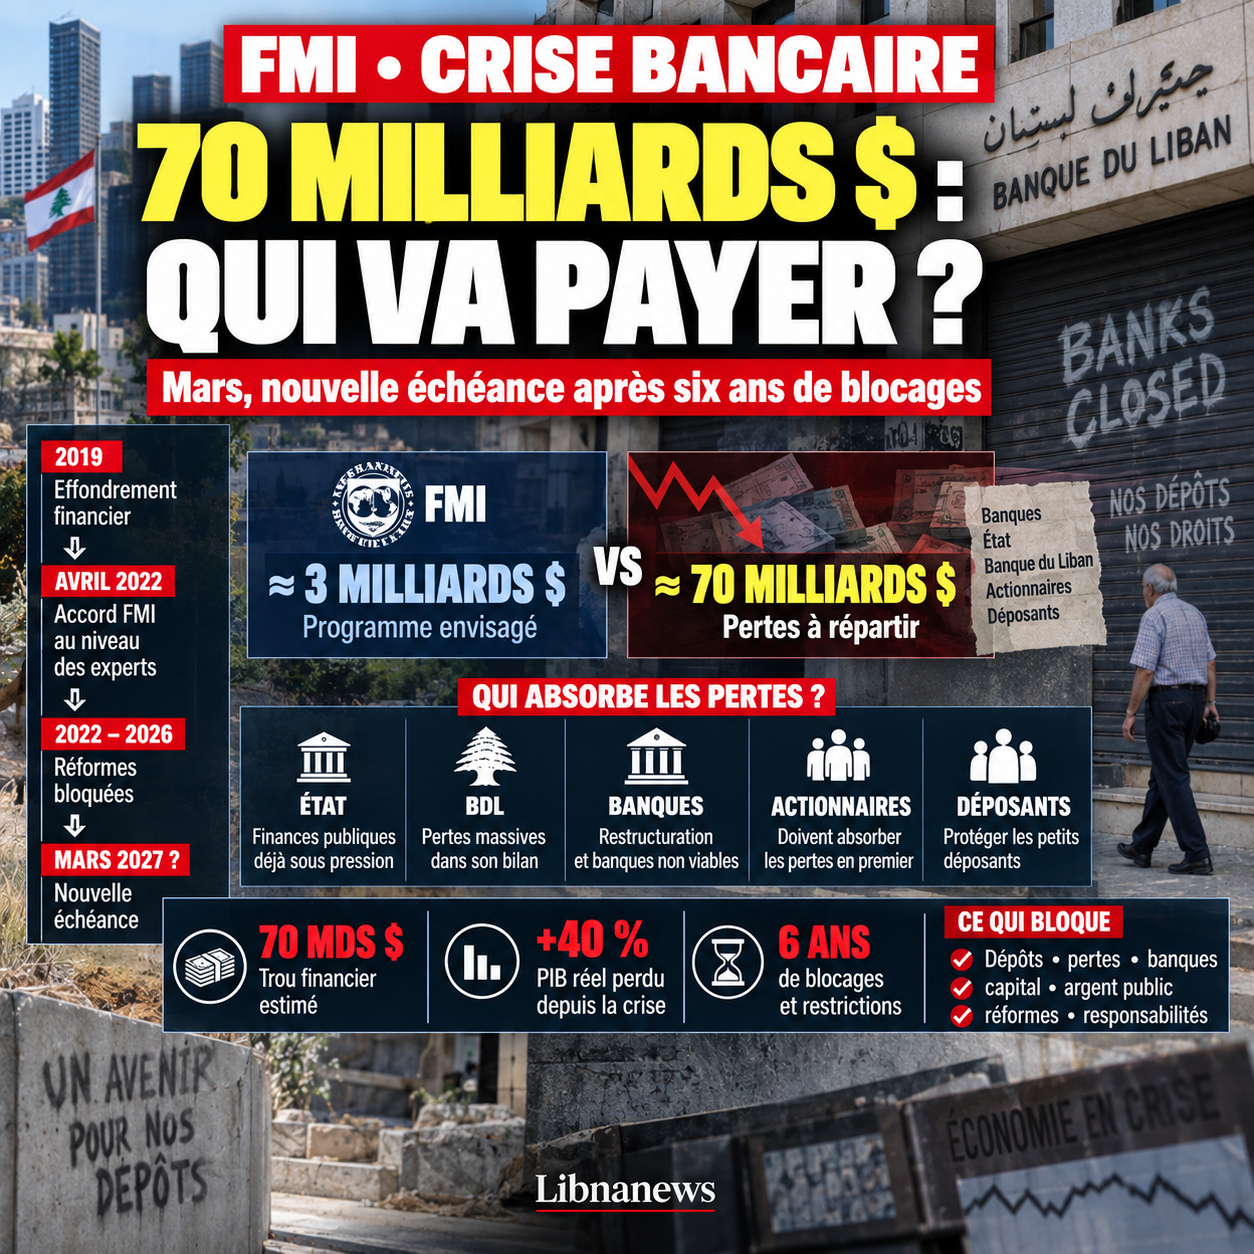
IMF: Why the March deadline is over $70 billion in losses and six years of blockages
March, a new date after four years of unfinished agreement
An agreement between Lebanon and the International Monetary Fund could be concluded next March. The deadline is now circulating in political and financial circles, while discussions have intensified on bank restructuring, deposit repayment and the budgetary framework for 2027. It comes especially after a major breakthrough on the banking resolution law, long considered one of the main obstacles to a programme with the Fund.
This perspective must, however, be placed in a history that began long before 2026. Lebanon had already concluded an agreement with the Fund at the expert level on 7 April 2022. The proposed programme covered approximately $3 billion and was expected to last 46 months. Four and a half years later, this agreement was never submitted under the conditions necessary to the Board of Trustees of the Fund to become an effective financing programme.
The problem was not the amount of 3 billion. The Fund first requested that Lebanon recognize the magnitude of the losses generated by the financial collapse of 2019 and decide who should bear them. Banks had to be restructured, small depositors protected, banks that were still viable and banks that were no longer viable had to be removed from the market. There was also a need to reform bank secrecy, establish formal capital control, restructure public debt and improve the governance of the Bank of Lebanon.
The core of the conflict has remained almost unchanged since then: approximately $70 billion in financial losses were to be distributed among the State, the Bank of Lebanon, commercial banks, their shareholders and, to some extent, depositors. This estimate already represented over 300 per cent of the estimated gross domestic product in 2022. Several economists now consider that actual losses are higher, especially after several more years of crisis.
The March timetable therefore depends not only on technical negotiations with the Fund. It depends on the ability of the political and financial system to resolve a battle that began in 2019 and that has contributed precisely to preventing the conclusion of the 2022 program.
IMF 3 billion hides 70 billion problem
The contrast between the two amounts makes it possible to understand the issue. Lebanon was negotiating financing of about $3 billion, while losses in the financial system were estimated at around $70 billion. The Fund’s program was never designed to fill this hole directly. The $3 billion was to serve as the anchor for a reform programme capable of restoring confidence and unlocking other international financing.
The main problem was therefore to recognize losses before seeking to finance them. This recognition immediately created a confrontation between the various actors. If the losses were recorded in the balance sheets, the equity of a part of the banks would disappear. Some banks had to be recapitalized. Others had to be liquidated. Shareholders had to absorb losses before they were transferred to the higher classes of creditors.
It is precisely this hierarchy that remains at the centre of the 2026 discussions. The principle in the negotiations is that depositors must not absorb losses before shareholders and subordinated creditors. It seems simple. Its application is much more complex because it determines directly who will pay for the collapse.
The banks lent heavily to the Bank of Lebanon, which itself financed a highly indebted State. When the system collapsed, customers’ deposits were still recorded in banks’ accounts, but a considerable part of the assets theoretically allowing repayment had disappeared or had become inaccessible. The debate on the « financial hole » was born from this chain.
Since then, each loss allocation proposal has led to opposition. Banks reject scenarios that could destroy their capital. Applicants refuse to pay for decisions in which they have not participated. The State seeks to limit the burden on public finances. The Bank of Lebanon itself must deal with the considerable losses accumulated in its balance sheet.
The agreement with the Fund has therefore been blocked for years by a much more political than accounting question: in what order should the managers and beneficiaries of the old system absorb the losses?
By 2022, eight conditions had been laid down before funding
The April 2022 agreement set out a particularly precise roadmap. The Council of Ministers was to approve a bank restructuring strategy immediately recognizing the sector’s losses. This strategy should protect small depositors and limit the use of public resources.
Parliament then had to adopt urgent legislation to resolve the banks in difficulty. Without this text, it was impossible to legally determine how to recapitalize a viable bank or liquidate an insolvent bank.
A third requirement concerned the country’s fourteen largest banks. They were to be subject, bank by bank, to an independent external evaluation. The objective was fundamental: to get out of the overall estimates and determine precisely the actual situation of each institution.
Parliament also had to reform bank secrecy. The Fund believed that the supervisory authorities should be able to access the information needed to restructure banks, combat corruption, administer taxes, investigate financial crimes and search for misappropriated assets.
At the same time, it was necessary to complete the special audit of the Bank of Lebanon’s foreign assets position, adopt a medium-term fiscal and debt restructuring strategy, vote on the 2022 budget and gradually unify exchange rates. The latter measure was to be accompanied by official capital control.
The whole was a coherent mechanism. First, we needed to know the real situation of the banks and the Bank of Lebanon. The losses were then recognized. Then divide them according to a defined hierarchy. Finally, the banking system could be restructured and the exceptional restrictions on deposits gradually replaced by a legal framework.
This programme was not implemented on time.
Capital control: the law comes after restrictions
The issue of capital control illustrates one of the strongest contradictions of the crisis. Banks have imposed restrictions on withdrawals and transfers since 2019. The depositors found themselves deprived of normal access to their money while no general law still regulated these restrictions.
Control therefore existed in practice before it existed in law. Conditions varied according to banks, accounts and periods. This situation has created a major inequality among depositors and has fed charges of transfers by certain persons with privileged relationships or access while the majority of clients were blocked.
The Fund requested a uniform law. It was intended to prevent further flight of financial resources and to ensure a more equitable distribution of withdrawal opportunities during restructuring.
The draft submitted to Parliament in March 2022 did not meet this requirement quickly. Discussions continued and successive versions were criticized. In 2023, again, the Fund considered that the capital and withdrawal control project required significant changes.
This delay was not neutral. While Parliament was discussing a statutory capital audit, de facto banking supervision continued. The depositors supported the restrictions without having the overall framework that would normally accompany the restructuring.
So the sequence was reversed. A measure that should have been temporary and framed has become a lasting reality, while the texts needed to resolve the crisis remain blocked.
Reformed banking secrecy, but not enough
The reform of bank secrecy has had a similar trajectory. A first amendment was voted in 2022, but was considered insufficient to allow for effective restructuring.
The problem was not to remove any bank confidentiality. The competent authorities should be given access to individual transaction and deposit data when necessary for supervision, restructuring, financial investigations or asset recovery.
Without this access, the real scrutiny of banks became much more difficult. It was also difficult to determine whether certain transfers had received preferential treatment at the time of the crisis.
The debate was particularly sensitive because bank secrecy had long been one of the pillars of the Lebanese financial model. Its reform therefore directly affected the interests of banks, but also those of economic and political leaders who had used the system.
The Fund acknowledged the improvements made to the text, while calling for several years to correct persistent weaknesses. Only gradually did the framework move closer to the standards required for restructuring.
This slow pace is important to understand why the 2022 agreement never came to an end. Each reform was dealt with separately, modified, referred back or partially adopted. The Fund called for a coherent package.
The 14 big banks and the test that was to reveal the losses
One of the most important conditions was the independent evaluation of the fourteen largest banks. It was intended to determine, on an establishment-by-establishment basis, the real quality of the assets and the ability of each bank to survive.
This step was essential to emerge from a collective fiction. Not all banks were necessarily in the same situation. Some could be recapitalized. Others might no longer be viable. Without an individual review, it was impossible to build a credible restructuring.
But the evaluation itself depended on political decisions on the banking strategy. The question was how the losses would be recorded and what rules would be applied. In the absence of agreement on these parameters, the technical work could not be completed.
This blocking effectively protected the status quo. Until banks were assessed according to a common methodology, no clear list of viable and unsustainable institutions could be established. Restructuring remained theoretical.
For bank shareholders, the stake was considerable. An independent assessment could lead to massive recapitalisation needs and, in some cases, loss of control of the establishment. On the contrary, it was essential for depositors to know which bank still had the means to repay part of its liabilities.
The delay in this assessment is therefore one of the points where financial interests and political delays have met directly.
Banks countered loss distribution
The resistance of the banking sector cannot be reduced to a rejection of any reform. The banks submitted their own proposals and challenged the plans they considered likely to impose an excessive share of the losses. But this battle had a concrete effect: for years no definitive mechanism of distribution could be adopted.
The Association of Banks has challenged several versions of government plans. One of the main subjects of confrontation was the possible use of public assets. The idea was, according to some proposals, to mobilize State-owned assets to help repay deposits or rebuild the banking system.
The Fund has been particularly cautious about this approach. The public assets belong to the entire population, including Lebanese who do not have large bank accounts. To use them massively to absorb the losses of the financial system would therefore be to transfer to all citizens part of the cost of a system whose benefits had been much more concentrated.
The issue is also the responsibility of shareholders. In a traditional banking restructuring, capital must absorb losses before depositors. Too fast use of public resources could reduce shareholder contributions and socialize losses.
It is precisely on this point that the conflict between the Fund and part of the banking sector has been the deepest. The Fund requires a hierarchy. Shareholders must pay before depositors. Unsustainable banks must be able to disappear. Public resources should be provided only within limits compatible with debt sustainability.
These principles directly affect the economic interests of bank owners. The Lebanese banking sector has historically maintained close relations with the political world. This proximity has complicated the adoption of legislation that could impose significant losses on shareholders.
Parliament as central to the slowdown
Several key reforms depended on Parliament. This turned the House into a decisive place in the process.
Capital control had to be voted on. The Banking Resolution Act was to be passed. Bank secrecy had to be reformed. Budgets had to be approved. Each of these files has experienced delays, modifications or controversies.
The problem cannot be attributed to a single parliamentary bloc. Oppositions have often gathered different interests. Some Members defended applicants and refused any text that might legalize a reduction in their rights. Others were close to bank interests. Still others refused government plans in the name of protecting the State’s assets.
This fragmentation has produced a common result: time has passed without global restructuring.
The economic cost of this slow pace was considerable. By 2022, the Fund warned that every delay would increase the cost to the population. In 2023, he still saw very little progress in implementing the preliminary measures.
Meanwhile, the economy was operating more and more in cash. Bank credit collapsed. Enterprises had to finance their activities outside the traditional system. Deposits remained blocked and banks lost their normal function of intermediation.
Gross domestic product cut by more than 40 per cent
The financial battle took place against the background of economic collapse. Between 2018 and the first years of the crisis, real gross domestic product fell by more than 40%. The pound lost most of its value and inflation reached three-digit levels over several years.
By 2020, inflation had reached about 84.3%. It rose to 154.8 per cent in 2021 and to 171.2 per cent in 2022. It peaked around 221.3 per cent in 2023 before slowing down. By 2025, it was down to about 14.6%. The regional war and the energy shock, however, caused a further acceleration in 2026, with about 17% over the first eight months of the year.
This development shows why bank restructuring is not a question for bankers and large depositors. The collapse of the financial system has accompanied a massive destruction of purchasing power.
The average monthly income used in a recent survey of Lebanese private sector workers who remained in employment was around $560, compared to about $668 before the last conflict, a decrease of 16.2 per cent. At the same time, a family of four people renting accommodation in Beirut or its suburbs may need between $1,400 and $1,500 per month only for housing, minimum power, electricity, water and transportation.
The gap allows the social cost of blocking to be measured. Bank restructuring did not take place, but the losses were nevertheless absorbed. They were affected by currency depreciation, falling incomes, restrictions on deposits, inflation and the deterioration of services.
2025 and 2026: the case finally begins to move forward
After several years of immobilization, a series of texts began to change the situation. In 2025, the restructuring of the banking system became a legislative priority. A new bank resolution law was passed to Parliament.
The question of the « financial hole » then returned to the centre of the debate. A project to organize financial stabilization and deposit recovery sought to allocate some $70 billion in losses among the various components of the system.
The text immediately met with resistance. The banks are in dispute. Political forces are opposed. Groups of depositors also expressed dissatisfaction that legal recognition of losses would turn part of their deposits into permanent losses.
This convergence of oppositions is revealing. Banks and depositors can fight the same text for exactly the opposite reason. The former may consider that they pay too much. The latter may consider that they do not recover enough. Political leaders then find themselves in between these two pressures.
Nevertheless, the Council of Ministers has made progress. The amendments to the Banking Resolution Act approved in 2026 were an important step. They now provide a framework for the orderly resolution or liquidation of establishments in difficulty.
This advance was expected since April 2022.
The last node: who will recover how much and in what order?
The main issue still open is now financial stabilization and deposit recovery. The debate with the Fund is about very concrete rules.
The first concerns the hierarchy of claims. No depositor should suffer a loss before shareholders and lower-ranking creditors. This rule must be recorded in a sufficiently clear manner to avoid the cost of restructuring being transferred too quickly to customers.
The second concerns liquidity. It is not enough to promise the gradual repayment of deposits. The banks and the Bank of Lebanon must have the resources to make these payments effectively. Too generous a timetable on paper, but without sufficient financial flow, would simply replace the current restrictions with a new promise that could not be kept. It is precisely for this reason that the discussion on deposits cannot be separated from bank restructuring, the recapitalisation of viable institutions and the treatment of banks unable to regain a sound financial position.
The third difficulty concerns the hierarchy of responsibilities. Since the beginning of the crisis, the Lebanese debate has often been presented as a confrontation between applicants and the State. This reading evacuates the other players in the channel. Banks have placed a considerable share of their resources with the Bank of Lebanon and the State, while paying for years some deposits at very high rates. The Bank of Lebanon, for its part, has used costly financial mechanisms to attract currencies and maintain the monetary system. The State has accumulated debt and deficits. A credible restructuring must therefore determine the respective responsibilities of each individual rather than turning the entire loss into a collective debt over future generations.
This is also the issue of bank shareholders. Restructuring in line with the principles defended since the beginning of the international discussions requires that existing own funds absorb losses before a burden is transferred to depositors or the community. This rule has given rise to strong resistance because it directly affects the value of holdings in banks. Some Lebanese banks have historically been linked to families with significant economic and political weight. Financial interests and political power relations are therefore common when it is necessary to decide who will be recapitalised, who will lose its participation and who will eventually have to leave the market.
Sustainable banks and banks that are no longer viable
The future agreement will not be able to avoid another question that has long been rejected: should all Lebanese banks be saved? The implicit response of the restructuring mechanisms is negative. The system must distinguish between those institutions which are likely to become viable again and those whose losses and inadequacies in own funds make it impossible to carry on business without a massive transfer of public resources.
This distinction explains the importance of individual assessment of institutions. One of the old commitments already provided for an examination of the fourteen largest banks. It was not just about producing an accounting photograph. The objective was to determine the real quality of assets, losses, liabilities to depositors and recapitalisation needs. Without this diagnosis, any restructuring remains theoretical, since no one knows exactly which establishments can survive and at what cost.
The delay on this site has protected the status quo. Until banks are classified according to their viability, they can continue to exist legally despite the inability of their clients to dispose of their funds normally. The banking system thus remains open without functioning as a normal banking system. Depositors own accounts receivable, but access to these claims remains limited by mechanisms imposed since the crisis.
The resolution of banks must put an end to this ambiguity. Sustainable banks will need to be recapitalized and comply with prudential requirements to resume normal business. The others will have to be restructured, merged or liquidated according to organised procedures. This will necessarily have an impact on bank owners and their control. This is also one of the reasons why its adoption has been so politically difficult.
Capital control, adopted after capital had already gone
The issue of capital control alone illustrates the shortcomings of crisis management. When banks began to limit withdrawals and transfers from 2019 onwards, no general law set the rules applicable to all. Each institution applied its own restrictions, with differences between clients and between account categories.
A real capital control law should have taken place at the beginning of the crisis in order to limit foreign exchange outflows, preserve available reserves and impose uniform rules. On the contrary, it has been the subject of long political and parliamentary battles. Meanwhile, control existed in fact for a large part of the depositors, but without a general legal framework and without preventing all capital outflows.
This delay created a deep breakdown in equality. Regular depositors were subject to restrictions while the issue of transfers during the early months of the crisis became one of the main subjects of controversy. When Parliament finally put forward the matter, part of the initial usefulness of capital control had already disappeared. Reserves had declined and confidence in the banking system was deeply affected.
This episode is essential to understand the mistrust surrounding new promises of reform. The problem was never only the absence of texts. He was unable to adopt them when they could still prevent some of the damage.
Banking secrecy, another parliamentary battle
The reform of bank secrecy has followed a comparable path. The Lebanese system had long made bank secrecy a central element of its financial model. After the collapse, its retention in too restrictive a form became incompatible with audit, control and accountability requirements.
Amendments were adopted, but their scope was the subject of criticism and requests for corrections. The problem included the real capacity of the competent authorities to access the information needed to review transactions, investigate financial flows and determine crisis-related responsibilities.
This issue directly affects the interests of many actors. A sufficiently broad lifting of bank secrecy facilitates the examination of transfers, relations between banks and politically exposed persons, as well as operations carried out before and during the collapse. It is therefore much more than technical reform designed to satisfy an international institution.
The resistance encountered shows once again the political nature of the reform programme. Each text that could improve transparency may also reveal information about the actors involved in its adoption. Parliament must then legislate on a financial system with which part of the political world has historically maintained close relations.
Parliament at the centre of structural conflict of interests
Reducing blockages to opposition between the Monetary Fund and the Banking Association would therefore be insufficient. A decisive part of the process is taking place in Parliament. Legislation necessary for restructuring must be passed, amended or supplemented. However, the parliamentary forces do not share the same view of the distribution of losses or the same interests.
Some currents emphasize full or maximum deposit protection. Others refuse to allow the State to bear additional debt to replenish bank balance sheets. Still others seek to preserve public assets. Behind these positions are real economic choices, but also social, financial and political interests.
The difficulty is compounded by the historical links between certain political figures and the banking sector. These links do not allow each Member to be regarded as the direct representative of a bank, and such generalisation would be unfounded. However, they explain why any reform that could erase the capital of bank shareholders, change the control of institutions or investigate certain transactions becomes extremely conflicting.
The result of these power relations was a succession of delays. Texts circulated between the government, the committees and the plenary. Some have been modified. Others were blocked. Competitive solutions have been proposed. Meanwhile, the loss did not disappear. It was gradually absorbed in a disorderly manner by depositors, employees and the economy.
The use of public assets, a major fracture line
One of the most important battles concerns the use of state assets. Part of the proposals defended in Lebanon in recent years have been to mobilize public assets or their future income in order to contribute to the repayment of depositors.
This solution has an obvious political force. It allows us to say that deposits will be progressively returned without immediately imposing a massive nominal loss. But it raises a question of fundamental justice: why should property belonging to the entire population be used to cover losses from a financial system whose profits have been deprived for decades?
Public assets are not a free reserve. Revenues from telecommunications, land, public enterprises or other assets also belong to citizens who did not have large bank deposits. To hire them for decades to repay certain debts would be to transfer part of the cost of the crisis to society as a whole.
The problem becomes even more important when these assets are the scarce resources that can finance infrastructure, social protection or reconstruction. Lebanon must now finance the recovery of the south, strengthen the army, modernize its public services and respond to a profound social crisis. Immobilizing a significant part of future public revenues to the financial system would reduce the capacity of the State to perform these functions.
This does not mean that no public assets can intervene in a solution. The question relates to their place in the loss hierarchy. If they become the primary source of repayment, bank shareholders and system managers can be relatively protected. If they only intervene after the absorption of losses by private capital and the restructuring of institutions, the logic is different.
March: a credible deadline or a new date?
It is in this context that the assumption of an agreement with the Monetary Fund appears in March. The date is close enough to be a political objective, but far enough to allow for several months of negotiations and legislative work.
The government now has some elements that did not exist at the beginning of the crisis. The Bank of Lebanon is headed by Karim Suaid. Discussions on banking restructuring are more advanced. The issue of financial flaw is openly addressed. The authorities can no longer claim that the system will spontaneously return to operation without recognition of the losses.
But the same fundamental obstacles remain. We have to decide who pays. The hierarchy must be established between shareholders, banks, the Bank of Lebanon, the State and depositors. The treatment of different deposits must be determined. Sustainable banks must be identified. The liquidity needed for repayments must be guaranteed. The corresponding texts must be adopted in Parliament.
So Mars will only be credible if these decisions begin to be taken before this deadline. A general political agreement will not suffice. The 2022 precedent has shown precisely that a technical agreement can remain ineffective for years when the prior actions are not carried out.
The social crisis now reduces room for manoeuvre
The government no longer negotiates in the context of 2022. The population has absorbed several more years of crisis. Revenues have been sharply reduced in real terms and the cost of essential services has increased.
A recent estimate places between $1,400 and $1,500 the monthly cost of housing, minimum power, electricity, water and transportation for a four-person family renting in Beirut or its suburbs. This amount does not include education, medical care, medicines, clothing or telecommunications.
At the same time, a survey of private sector workers conducted in May 2026 estimated the average monthly income of Lebanese workers remaining in employment in the sample studied at approximately $560, compared with $668 before the March conflict, a decrease of 16.2 per cent. Even with two workers each receiving this amount, family income reaches $1,120 and remains below the estimated cost of the five basic needs.
Inflation in the first eight months of 2026 reached about 17%, while expectations at the beginning of the year were much lower. The cost of private electricity has risen sharply. Medical expenses incurred directly by households now account for a much larger proportion of invoices than before 2019.
Under these conditions, any banking solution that still transfers losses to the population becomes politically explosive. The government cannot simultaneously ask households to bear the rising taxes, the deterioration of public services and a further reduction in the value of their savings without creating a major challenge.
Budget 2027 complicates the equation
Draft budget 2027 shall be issued at the same time. The State is seeking to increase its revenue while the contributing capacity of a large part of the population is already extremely low. The use of indirect taxes remains particularly contested, as they affect consumption regardless of the level of wealth.
This policy is directly related to the banking file. If the State increases the levy on the population in order to finance its operation while simultaneously mobilizing its assets to cover the losses of the financial system, the question of the distribution of sacrifices will become impossible to avoid.
Negotiations with the Monetary Fund cannot therefore be separated from a broader fiscal policy. Bank recovery means that if it is part of an economy capable of regaining growth, generating government revenue and generating income.
A financial agreement that would stabilize banks without restoring public services and purchasing power would remain socially fragile. Conversely, no sustainable social policy can be financed as long as the State and the banking system remain paralysed by accumulated losses.
The credibility of the agreement will depend on what changes before it is signed
The assumption of an agreement in March must ultimately be judged less on the date itself than on the decisions taken in the coming months. Lebanon has already seen the announcement of a preliminary agreement with a specific list of reforms. Four years later, most of the banking problem remains open.
This time, credibility will require prior action. Losses must be recognised in a transparent manner. Banks will have to be evaluated individually. Shareholders will have to take their place in the loss hierarchy. Unsustainable settlements will need to enter into a resolution mechanism. The treatment of deposits should be based on identified resources and not on accounting promises.
Parliament will also have to show that it can adopt texts which are not emptied of their substance by compromises between competing interests. This is probably where most negotiations will be held. International missions can propose models, calculate funding needs and evaluate bills. They cannot replace a Lebanese political decision on the distribution of losses.
Banks will have to accept that a return to the situation before 2019 is impossible. The sector that will emerge from restructuring will necessarily be different: less institutions, more real capital, stricter prudential rules and a different relationship with the State and the Bank of Lebanon.
Finally, applicants will have to obtain a visibility they have been missing for seven years. They need to know the amount recoverable, the timing, the currency of repayment and the guarantees to ensure that commitments are actually honoured.
It is only when these elements come together that March can represent something other than an additional deadline. The Lebanese problem is no longer to arrive at a text announcing an agreement with the Monetary Fund. Such a text has existed in principle since April 2022. The real change would be to finally accept the consequence that the political and financial system has delayed since the beginning of the crisis: losses exist, they cannot be erased by decree, and any reconstruction of the banking sector begins by clearly deciding who is responsible.