
The debate on deposits masks the most difficult issue
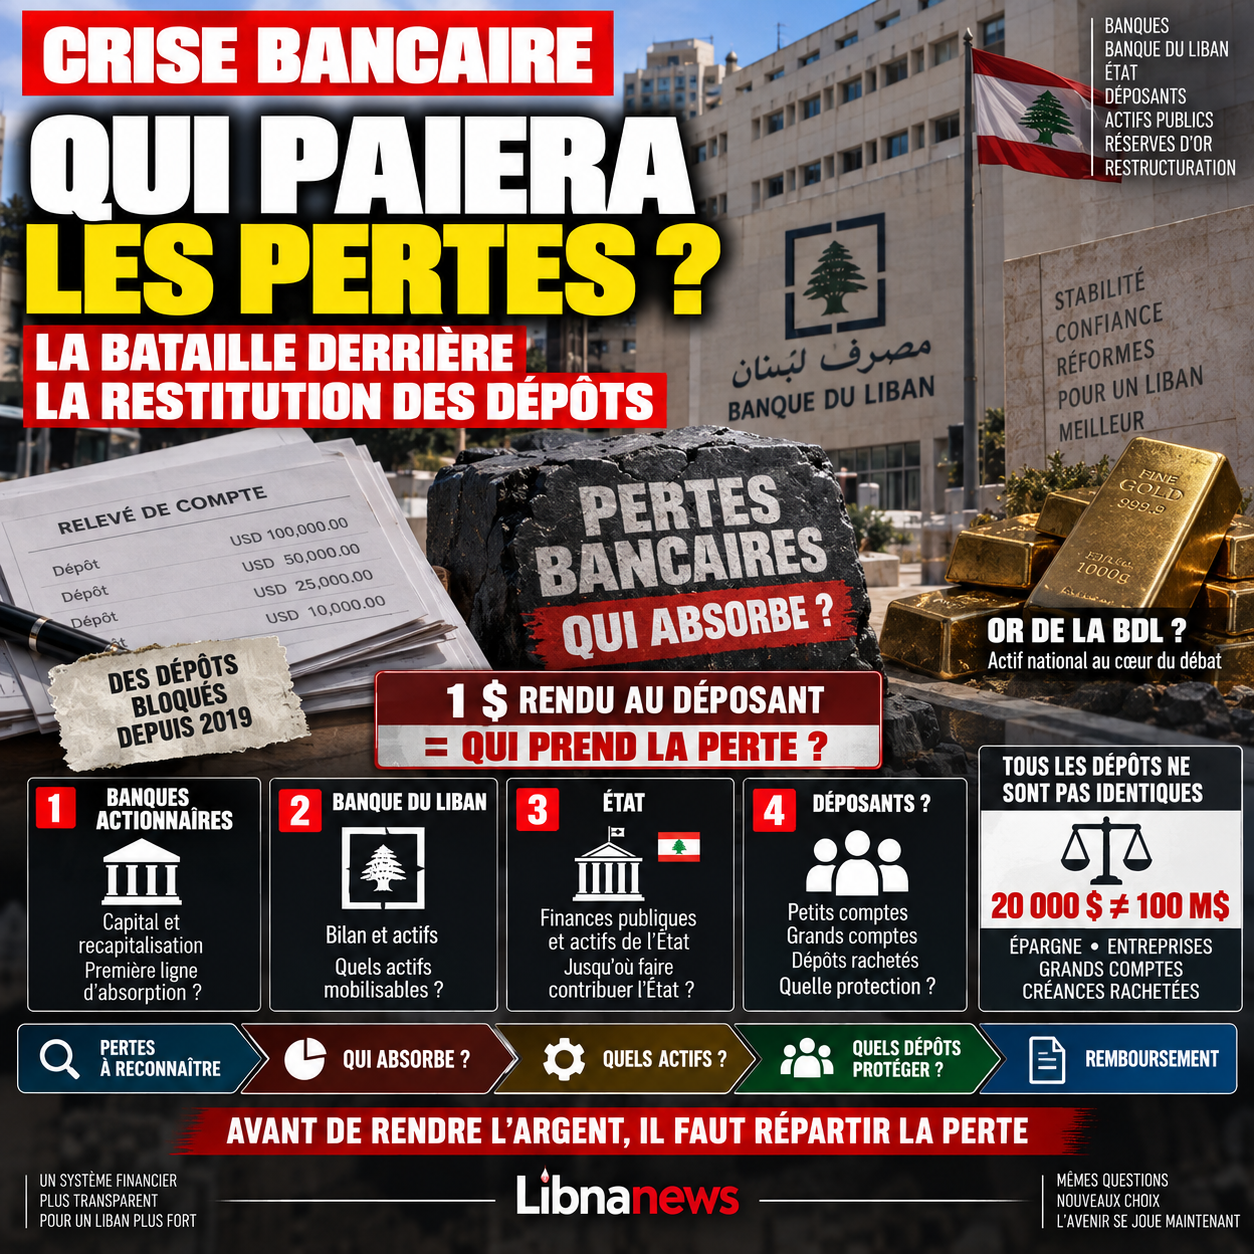
The debate on the draft treatment of financial losses focuses on an issue that is immediately understandable to applicants: how much will they recover and within what time frame? Yet the most important technical and political problem lies upstream. Before determining how to return the deposits, Lebanon must decidewhich will bear the accumulated losses in the financial system, and in what order.
This hierarchy is not an accounting detail. It determines the distribution of several tens of billions of dollars of losses between banks and their owners, the Bank of Lebanon, the State and, ultimately, depositors. However, the evidence examined in the sources of 23 September 2026 shows that this issue remains one of the most sensitive aspects of the system under preparation.
The Government of Nawaf Salam claims to have begun the process of processing the « financial gap », along with bank restructuring and the lifting of bank secrecy. The Prime Minister presents this text as one of the instruments necessary for the return of deposits and the conclusion of an agreement with the International Monetary Fund.
But returning a deposit is only the last step in the problem. In the past, it is necessary to determine what actually remains in the system, recognize losses, allocate losses and decide which assets can finance repayments. As long as this sequence is not clearly defined, a promise of restitution can simply shift losses from one balance sheet to another.
The crisis mechanism explains why the distribution is so conflicting
In the years prior to 2019, commercial banks attracted large dollar deposits. A considerable portion of these resources were then placed with the Bank of Lebanon. The central bank directly or indirectly used these currencies to finance the economic system, support the pound, meet external needs and support state financing.
When capital inflows dried up, the mechanism ceased to function. Banks still had large debts on the Bank of Lebanon in their books. Depositors still had legal claims on banks. But the currencies corresponding to a large part of these liabilities were no longer available.
It is the heart of the financial gap.
The problem cannot therefore be solved simply by ordering banks to return the money. In order to fully repay their clients, they should themselves recover all their debts from the Bank of Lebanon. The central bank, in turn, cannot honour all these liabilities without having the corresponding assets or transferring part of the burden to the State.
So every possible solution leads to someone.
If the bank pays, its shareholders and equity are affected. If the Bank of Lebanon absorbs the loss, its balance sheet must be restructured. If the State intervenes, the charge is transferred to the taxpayer and to public finances. If none of these levels are sufficient, the applicant will eventually bear part of the shortfall.
The political battle is precisely about the order in which these pockets must be sought.
Bank shareholders are normally the first line
In a traditional banking restructuring, bank owners bear losses before ordinary depositors. Capital exists precisely to absorb shocks.
This logic is simple. A shareholder invests in a company to benefit from its profits when it operates. In return, it bears the risk of losing its investment when the company becomes insolvent.
Applied in Lebanon, this principle implies that banks’ existing own funds must be used before a loss is imposed on depositors.
But the question quickly becomes more complicated. What was the real value of bank equity after the collapse of the pound? What assets can still be valued? Do some shareholders have the ability to inject new capital? And above all, should a bank unable to recapitalize continue to exist?
It is here that the bank restructuring project directly joins the one on financial losses.
A viable bank can be recapitalised and continue to operate. A bank whose losses far exceed available assets should normally be restructured, merged, sold or liquidated in an orderly manner.
Artificially maintaining all banks in operation is tantamount to delaying the recognition of losses.
The question of capital coming out before and during the crisis remains a must
Shareholders’ liability is not limited to the present value of their interests.
Since 2019, there has been a regular question: have some shareholders, directors, officers or politically exposed persons transferred significant amounts abroad at a time when other depositors’ access to their accounts became progressively impossible?
Of course, not all capital outflows are illegal. Lebanon had not immediately adopted formal capital control. A person could therefore make a legal transfer while possibly benefiting from bank access that other customers no longer had.
The problem is that of equal treatment and, in some cases, the origin of the funds.
Judicial proceedings in Lebanon and Europe are of particular importance here. They examine various financial movements involving former officials, bankers, intermediaries and institutions. They do not lead to the conclusion that all disputed transfers must be recovered. However, they show that the restructuring of the system cannot be completely separated from the search for assets that would have left the country under disputed conditions.
For depositors, the principle is politically obvious: it would be difficult to accept a reduction in their assets before the responsibilities of system owners and managers were examined.
The Bank of Lebanon concentrates most of the problem
Even a maximum contribution from bank shareholders would probably not be enough to fill the gap. The heart of the losses lies in the relationship between commercial banks and the Bank of Lebanon.
For years, banks have placed a considerable part of their liquidity with the central bank, attracted in particular by high yields. These transactions created large bank claims on the Bank of Lebanon.
The question then becomes: what is this debt worth today?
If fully recognized, the Bank of Lebanon must find the necessary assets to repay it. If reduced, banks have an additional loss, which is then passed on to their own balance sheet and thus to their ability to repay depositors.
The restructuring of the Bank of Lebanon is thus inseparable from that of the banks.
Governor Karim Souaid inherits a balance sheet deeply affected by the operations accumulated in previous years. The new management must simultaneously preserve available reserves, rebuild the credibility of the institution and participate in the settlement of historical liabilities.
Using the current assets of the central bank to repay old deposits without limitation would create another problem: depriving the future monetary system of its reserves.
So the debate is not just about what the Bank of Lebanon has. It focuses on what it can mobilize without compromising its future function.
Inevitably back in the discussion
Gold reserves are one of the Bank of Lebanon’s most visible assets. Their high value leads regularly to propose their use to help settle losses.
This solution seems attractive because it turns sleeping assets into a source of repayment.
It is much more complex in practice.
It is a national reserve and its use is legally regulated. Selling it to finance bank losses would mainly be to turn a long-term collective asset into an immediate payment to deal with the consequences of a past crisis.
The choice is therefore political as well as financial.
If gold reserves are used, it is necessary to determine which generation bears the loss of this asset and to whom precisely its liquidation benefits. If they are not, other resources must be found.
The same debate concerns the other assets of the Bank of Lebanon and any interests or properties that may be valued.
The risk is to build a repayment plan on assets whose sale would be legally, politically or economically difficult.
Can the state be made responsible for the difference?
This is the other great battle.
Part of the banking system considers that the State bears a major responsibility because a fraction of the financial resources have been used directly or indirectly to finance its deficits. According to this reading, the Treasury should participate in the treatment of losses.
The opposite reasoning points out that the transfer of bank losses to the state ultimately amounts to paying them by the entire population.
The State does not have a reserve of money outside the company. Its resources come from taxes, public assets and future income.
A massive budget assumption would therefore turn a financial loss already incurred into public debt or future levies.
This issue becomes particularly sensitive when the State’s assets are mentioned.
Public land, public enterprises or future income may theoretically be allocated to a repayment mechanism. But such a solution means that assets belonging collectively to the Lebanese are used to repair the losses of a banking system that not all citizens have benefited in the same way.
This is why the formula of creating a fund financed by public assets is regularly resisted.
Not all deposits are the same problem
Another key issue concerns the distinction between applicants.
Treating a $20,000 savings account in the same way and a deposit of several hundred million would create a very different distribution of losses.
Banking resolution standards generally seek to further protect small depositors. Large creditors may be more exposed when assets are no longer sufficient.
But the Lebanese crisis has a peculiarity: for years, the banking system was presented as safe, while no orderly resolution mechanism was applied at the time of the collapse.
Many large applicants are also companies. Strongly reducing their assets can cause bankruptcies, eliminate jobs or prevent investment.
The size of the deposit must therefore be distinguished from the nature of its holder.
A family that has sold real estate may have a high deposit without being a financial investor. A company can keep its cash in bank to pay its suppliers. A fund or a professional investor is in a different situation.
A serious law must therefore define its categories with much more precision than just opposition between « small » and « big » applicants.
Interest paid before 2019 may also enter the debate
Another sensitive issue is the very high yields proposed before the crisis.
Some deposits benefited from interest rates much higher than those available on international markets. These returns were one of the instruments used to attract dollars into the system.
Should all accumulated interest be regarded as an identical debt to the original capital?
The answer is not obvious.
A depositor can legitimately argue that he has accepted a bank’s contractual offer and that he has no responsibility for the monetary policy that allowed that return.
Conversely, in a restructuring where assets are insufficient, the treatment of exceptionally high interests may become an instrument for reducing the gap without affecting initial capital in the same way.
This distinction can be billions.
It is therefore much more important than some secondary discussions that occupy the public debate.
Deposits processed after 2019 are still a different category
The crisis also created several types of bank dollars.
After 2019, deposits were purchased and sold with significant discounts. An investor could acquire a bank claim of $100,000 for a fraction of its face value.
If the law then repays these $100,000 at their full value, the buyer realizes a considerable profit financed by the resolution mechanism.
It is therefore necessary to distinguish the original applicant from the one who subsequently purchased a haircut claim.
The date of acquisition, the price paid and the origin of the deposit can become decisive.
This is one example of why a simple repayment threshold is not enough to resolve the crisis.
Two accounts with exactly the same balance may correspond to completely different economic realities.
The real risk is to allocate losses before recognizing them
Lebanon spent several years discussing the crisis without adopting a definitive and consensual recognition of all losses.
Yet this is the first step in any resolution.
It is necessary to establish the real value of the banks’ assets, their claims on the Bank of Lebanon, its liabilities, the mobilizable assets and any government bonds.
Without a credible consolidated balance sheet, the distribution can be manipulated by the assumptions made.
An optimistic valuation of assets artificially reduces loss today but risks creating a new hole tomorrow. Overly pessimistic valuation can, on the contrary, immediately impose greater losses than necessary.
The role of audits therefore becomes central.
Restructuring cannot be based solely on political negotiations between the State and banks. It must be based on an assessment that is strong enough to withstand challenges.
The order of losses is the real law of the crisis
The heart of the future mechanism can finally be summarized by a succession of questions.
What share must first be absorbed by the capital of banks? Which shareholders must recapitalize their institutions? Which banks are still viable? What assets can be recovered in court proceedings? What part of its commitments can the Bank of Lebanon recognise? What central bank assets can be mobilised? How far can the state contribute without transferring losses to taxpayers? Which deposits should be fully protected? How to deal with large accounts, exceptional interest and receivables acquired at reduced prices after the crisis?
The order in which these questions will be decided will determine who will actually pay.
Therefore, the public debate focused solely on the number of years needed to return the deposits is insufficient. A repayment schedule can be announced without clearly defining the source of money.
The real political choice is before the first payment.
It consists of deciding whether the losses will first be borne by those who owned and administered the financial institutions, by the balance sheet of the Bank of Lebanon, by the public assets or by the depositors themselves.
As long as this hierarchy is not explicitly set, the promise to return the deposits remains incomplete. Behind every dollar promised to a depositor remains the same question, the one that six years of crisis have still not settled definitively:on what balance sheet will this dollar be taken, and who will accept the corresponding loss?