

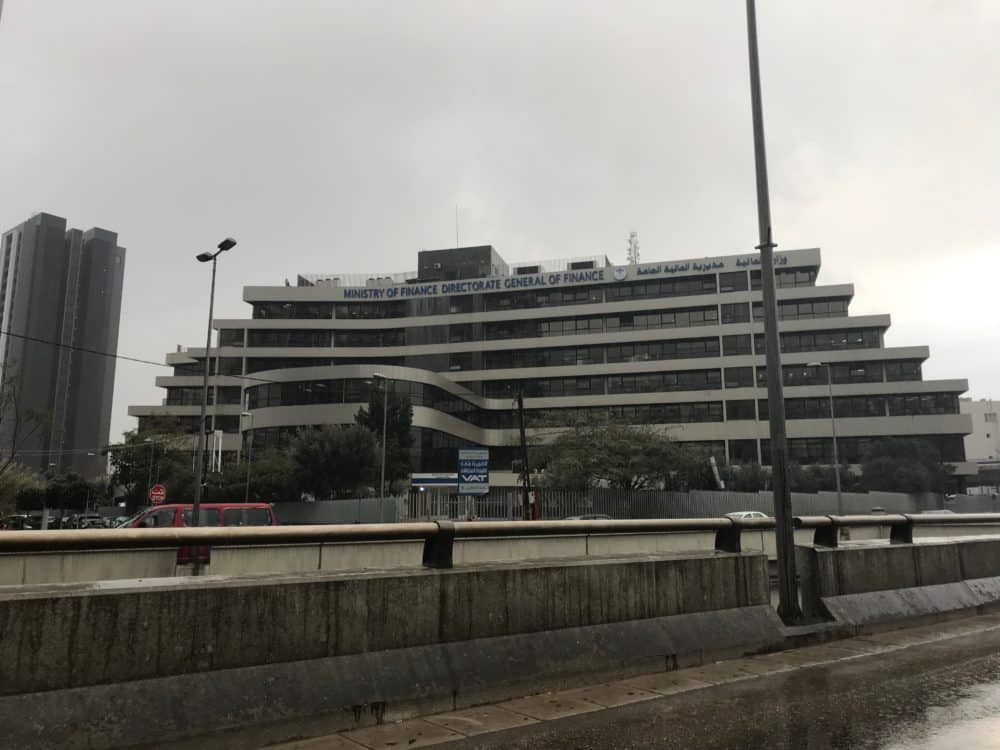
The Ministry of Finance forwarded to the Finance Department the files of 107 companies and institutions that failed to meet their tax obligations. In an interview published by Ad Diyar on November 2, 2026, Yassine Jaber states that these referrals followed warnings and payment requests. Other files remain subject to verification. However, the Minister refuses to announce the amounts expected before the completion of the judicial reviews and proceedings.
This announcement deals with cases referred to the courts, not convictions. Nor does the number advanced represent the totality of tax offences in Lebanon. Jaber himself stresses this in the interview: he does not want to measure the results of his action to the number of prosecutions alone. Its stated objective remains to obtain more spontaneous payments, without having to initiate proceedings against each company.
VAT collected does not constitute an enterprise’s revenue
The Minister identifies two situations. The first concerns the failure to pay income tax. In this case, the company must pay a levy calculated on the results of its activity. The second concerns value added tax levied on consumers but not paid to the Treasury. Jaber described this last situation as more serious.
According to its explanations, VAT collected on behalf of the State is not part of the company’s own funds. Nor is it an income freely available to it. The taxpayer then retains an amount already deducted from the consumer, whereas it had to join the public revenue.
Receivables still to be accurately established
The number of files should not be confused with an estimate of the proceeds of recovery. When asked about the amounts involved and their effects on public revenues, Yassine Jaber remains cautious. « We will not announce a figure until it is final, » he says.
The Minister explained that the amounts must be determined after audits and court proceedings. In his view, announcing an estimate too early could damage businesses or create unrealistic expectations. He claims that the files relate to amounts actually due, without publishing a total immediately available from the Treasury.
Justice as a last resort
The discourse of firmness is accompanied by the possibility of regularisation. Jaber claims that judicial referral is a last resort, not the first administrative step. It indicates that it has made decisions to address and reduce tax penalties to facilitate institutional compliance.
The Minister intends to distinguish those facing real difficulties from those deliberately seeking to escape payment. This distinction is important in its arguments. It does not present every delay as evidence of a will to fraud, while refusing that economic difficulties justify all situations.
Simplify approaches to expand compliance
Jaber describes two complementary lines of work. The first is to make compliance simpler. The Ministry works in particular on electronic invoicing, designed to automatically document sales; It is a project, not a widespread deployment announced. He cited the reduction of procedures, the extension of electronic services and returns, and the cleaning of the tax register. In particular, it is intended to deal with the presence of fictitious or inactive companies.
The Minister also referred to faster and simpler approaches for taxpayers who meet their obligations. He hoped that such compliance would produce a concrete advantage, rather than remain an administrative requirement without any visible counterpart.
The second focuses on more focused monitoring. Jaber contrasts a risk-based approach to random controls. It describes a comparison work between returns to the tax administration and data from customs, land registry and other sources.
The cost of the informal exceeds the revenue lost
Yassine Jaber puts recovery into a wider problem: the place of activities that remain outside the organized system. According to him, they deprive the Treasury of revenue, but also penalize those who work there. He mentioned in particular their lack of social protection.
Jaber recognises that not all non-registered institutions are necessarily subject to a premeditated desire for fraud. Some feel that the constraints of entry into the organised economy outweigh the benefits they might derive from them. His answer is to make recording more accessible, while increasing the cost of keeping it out of the system.
Fairer competition for companies paying
Jaber states that compliant taxpayers bear a double burden when others escape the levy. They pay their taxes, but also face competitors who can sell cheaper because they do not pay the same obligations. Recovery is therefore presented as an issue of competition, not just of public revenue.
The Minister adds that every book recovered from defaulting taxpayers can avoid asking for more from those who already pay. However, this reasoning is not an announcement of a reduction in taxes.
To support the stated private sector, Jaber highlights three conditions: a fair market, quick and clear administration, and effective recognition of compliance. It believes that support for businesses should not be limited to exemptions. Simplification of procedures and the fight against irregular competition are thus central to its response.
Finally, it wishes to strengthen the link between contracts with the State and tax regularity. With this in mind, a document attesting to the good situation of the taxpayer must become an advantage in competition for public procurement.
Sources
Ad Diyar, November 2, 2026, page 3.





Comments