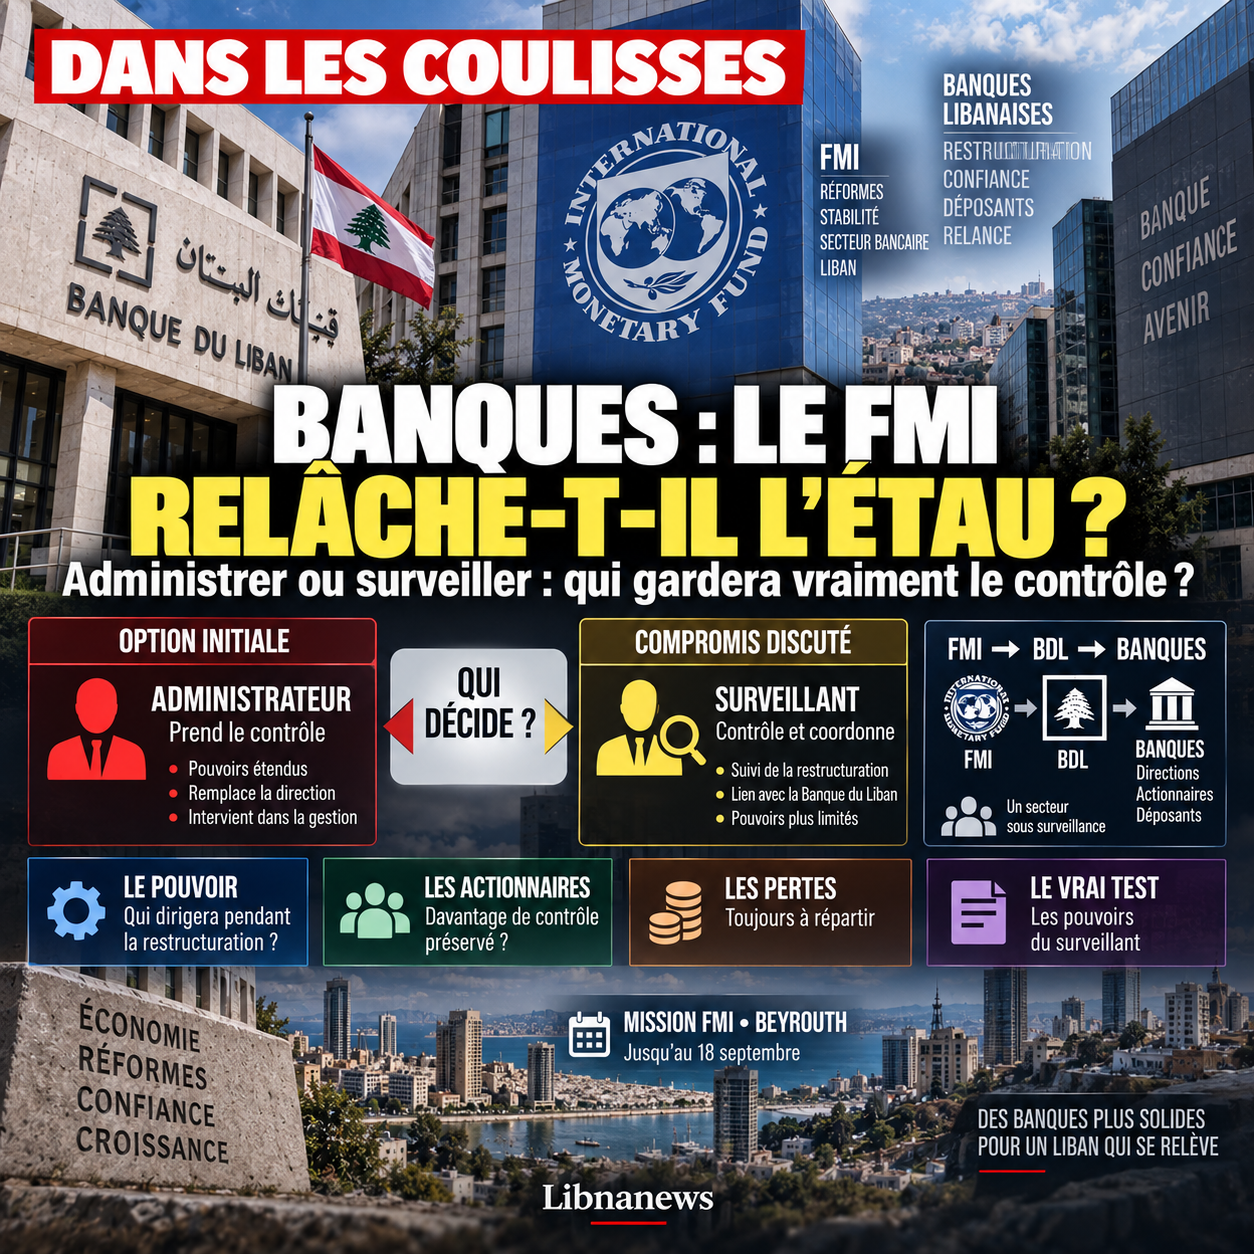
Discretionary developments in discussions between the International Monetary Fund, the Bank of Lebanon and the banking sector could profoundly alter the methodology used to restructure Lebanese institutions. Al Akhbar of 15 September 2026 reports that an intermediate formula is now being examined: instead of entrusting each bank concerned to a temporary administrator with broad powers, a supervisory officer could be appointed to monitor its restructuring and coordinate its activities with the Bank of Lebanon. Behind this technical difference is a much more important question:who will really retain control of the banks during their restructuring?
The IMF initially defended temporary bank administration
According to Al Akhbar of 15 September 2026, bank restructuring remains one of the main points of discussion with the Monetary Fund. The problem is not just to determine which banks can continue to operate. It is also necessary to define the governance regime to be applied to them during the restructuring period.
The original formula would have been much more binding on shareholders and current management. The Fund would have liked a temporary administrator to be placed at the head of each institution undergoing restructuring. It would have sufficient powers to intervene directly in the management of the bank.
In particular, the aim would be to prevent the managers and shareholders who led the institutions before and during the crisis from continuing to control their own restructuring.
The question is central. Bank restructuring usually involves recognizing losses, re-evaluating assets and determining capital requirements. It can also lead to changes in ownership structure and direction.
It is therefore a clear governance problem to entrust this process to the same actors who already control the institution.
The temporary administrator formula would create a net break. During the restructuring, the bank would no longer be fully run by its owners or its usual management.
But this option directly affects the interests of shareholders. It is precisely on this ground that a new formula would have emerged.
An intermediate solution would now be on the table
Al Akhbar reports that a different proposal is being discussed. Instead of a temporary administrator with very broad executive powers, each bank concerned could host a person responsible for monitoring the restructuring.
Its role would be mainly that of a supervisor and coordinator.
It would act as a link with the Bank of Lebanon and monitor the implementation of the restructuring measures. Its powers would, however, be less than those of a director who would take direct management of the institution.
This difference may seem limited. She’s not.
In the first scenario, owners and managers would lose much of their operational control during the restructuring.
In the second, they could retain a much greater place in day-to-day management, under the supervision of a representative responsible for verifying compliance with the new rules.
The intermediate formula would therefore be a compromise between two contradictory imperatives: strengthening control over banks without causing a total and immediate eviction of their leaders.
Al Akhbar presents this development as the result of the ongoing discussions. It is not announced as a final decision of the Monetary Fund or the Bank of Lebanon.
This reserve is important. The corpus makes it possible to speak of anegotiated formulano mechanism already adopted.
Behind the choice of title is the question of power
The difference between « administrator » and « supervisor » may give the impression of a secondary legal debate. However, it determines the distribution of power in restructured banks.
A temporary administrator may make decisions. An overseer can especially control those taken by others.
In the first case, current leaders lose part of their ability to act. In the second, they may continue to perform their duties as long as they comply with the rules imposed by the process.
This distinction becomes particularly important when deciding on the value of assets, the treatment of shareholders and how to recapitalise.
The person controlling the bank during this period necessarily has an influence on how these decisions are prepared and executed.
Al Akhbar therefore sees governance as one of the real battlefields of restructuring.
The Monetary Fund would seek to prevent the process from being controlled by those whose past decisions are related to the current situation in the sector. The owners would instead seek to avoid complete dispossession.
Between the two is the Bank of Lebanon, led by Karim Suaid, which must play a central role in the supervision of the sector and in the implementation of the future scheme.
The Bank of Lebanon would become the centrepiece of the compromise
The formula referred to by Al Akhbar would mechanically strengthen the role of the Bank of Lebanon. If the head appointed to each institution is primarily responsible for monitoring and coordination, the central supervisory authority becomes essential.
The Bank of Lebanon should receive information, monitor the implementation of measures and intervene when commitments are not met.
That moves part of the problem.
The question would no longer be whether the shareholders retained control. It would also be necessary to determine what powers the Bank of Lebanon actually has to impose restructuring when an institution resists.
The device can only function if the criteria are clearly defined.
A bank needs to know what levels of capital it needs to reach. She must know the schedule. The conditions for continuing its activity must be precise. The consequences of failure must also be established.
Without these elements, a supervisor may become an administrative intermediary with limited means to impose changes.
The effectiveness of the compromise would therefore depend less on its designation than on the legal powers attached to the function.
Shareholders seek to avoid total eviction
Al Akhbar clearly places the interests of bank owners at the heart of the negotiations. The sector seeks to preserve some of its capital and power in institutions that will survive restructuring.
This position is understandable from the shareholders’ point of view. Restructuring can result in significant losses on existing capital. In some cases, it may lead to massive dilution or to the disappearance of the participation of current owners.
But this defence of shareholders comes up against another question: liability in the accumulation of losses.
The newspaper believes that the Monetary Fund wants to prevent a restructuring that would put the bulk of the effort to other actors while leaving the owners’ position intact.
The choice of governance mechanism becomes a means of dealing indirectly with this responsibility.
Placing a bank under temporary administration means that owners cannot decide alone how losses will be recognized.
Maintaining management under supervision leaves them more room.
That is why the compromise currently mentioned could represent an important concession to the banking sector, according to Al Akhbar.
However, this assessment must remain attributed to the newspaper. The sources provided do not contain a statement from the Monetary Fund acknowledging that it has transferred to the requests of the bank owners.
The compromise does not resolve the fundamental issue of losses
Even if agreement is reached on governance, the central problem of the banking crisis remains: how the losses will be distributed must be determined.
The appointment of a director or supervisor does not create new capital.
It does not automatically return deposits.
Nor does it alone regulate commitments between banks, the Bank of Lebanon and the State.
The governance mechanism is used to administer restructuring. It does not replace the restructuring itself.
That is precisely what makes the discussion important but insufficient.
The future system will have to determine which banks are viable. Some may require additional capital. Others may have to merge, reduce their size or exit the market.
The treatment of shareholders must also be defined.
Finally, the fate of applicants will remain politically and socially central.
The corpus of 15 September provides more details on the governance mechanism than on the final loss allocation formula. It would therefore be incorrect to conclude that the Fund and the Lebanese authorities have already reached a comprehensive agreement on the banking sector.
IMF mission to Beirut gives immediate importance to confidence
This indiscretion appears at a time when a delegation from the Monetary Fund begins a new series of meetings in Lebanon.
Al Sharq of 15 September 2026 states that the mission must continue its work until 18 September. The Department of Finance is one of the main centres of discussion. Representatives of the Fund must meet with the authorities and bodies involved in economic and financial reforms.
The timetable is therefore particularly interesting.
The formula revealed by Al Akhbar does not appear as a remote hypothesis. It comes at a time when Lebanese officials and the Fund must resume their discussions.
The following days can therefore be used to determine whether this compromise is progressing.
The government of Nawaf Salam better get a breakthrough. Banking restructuring requires a significant part of the return to normal financial activity. It also influences the relationship with international donors.
For the Fund, the challenge is to avoid a political agreement producing only formal restructuring.
For banks, the objective is to survive the reform without losing complete control of their institutions.
The announced return of credit makes restructuring even more urgent
Ad Diyar of 15 September 2026 announces at the same time that the loans of the Public Housing Foundation could resume in early 2027, with a ceiling of up to $100,000.
This information gives a very concrete dimension to the banking debate.
Lebanon cannot function sustainably with a financial system unable to provide long-term credit.
Financing for housing, business and investment depends on institutions capable of collecting resources and lending within a stable framework.
The return of certain credit mechanisms may be a sign of standardization. But it cannot become sustainable if the restructuring of the banking sector remains unfinished.
The issue of governance, therefore, is not limited to bankers and the Monetary Fund. It affects the future ability of the economy to regain a financing system.
A relaxation that could be politically explosive
If the formula reported by Al Akhbar is confirmed, it could cause significant controversy.
The proponents of the compromise will be able to argue that it avoids too brutal a takeover of banks and preserves the continuity of their operation.
They may also argue that a supervisory officer with sufficient powers can effectively control restructuring without systematically replacing all branches.
Critics will be able to answer that this solution allows current officials to maintain excessive influence after a crisis that has immobilized the savings of a large part of the population.
The debate will therefore move quickly from the technical terrain to that of responsibility.
Who should lose control when a bank is no longer viable?
Should shareholders be excluded before using other resources?
What power should the historical direction be?
Who represents the interests of depositors during the restructuring?
The supervisor’s formula does not yet answer all these questions.
The decisive point will be the real extent of the powers of the future overseer
The confidence of Al Akhbar must therefore be followed with precision.
The mere replacement of the word « administrator » with « supervisor » does not make it clear whether the Monetary Fund has actually relaxed its position.
It will depend on the powers given to that person.
If it can block decisions, require changes, access all data, impose a timetable and seize the Bank of Lebanon in case of non-compliance, the difference with a temporary administration may be less than it appears.
If its role is limited to observing, drafting reports and coordinating exchanges, the compromise would represent a much more substantial concession to the owners.
So it’sthe legal content of the function, not its title, which will measure the real scope of change.
At the moment, sources show thata formula less intrusive than full temporary administration would be discussed. They do not make it possible to state that it has been definitively accepted by the Monetary Fund or that a comprehensive agreement on bank restructuring has been concluded.
This is precisely what makes this confidence important: if it is confirmed during the discussions of the Fund’s mission to Beirut, it could become one of the main compromises determiningwhich will control the lebanese banks during their restructuring and how far the current owners will retain their influence.